
Setting Up Your Self-Directed Account
- Choose a specialized custodian. Mainstream brokerage houses usually do not hold private securities, so you need a specialized custodian that supports alternative assets like private equity, real estate partnerships, and promissory notes.
- Select the account type. Determine whether you are rolling over a pre-tax traditional account, establishing a Solo 401(k), or using a Roth structure. Many high earners take advantage of backdoor conversions to place capital where it can grow tax free. To explore these options, read Can I use a Roth IRA for private deals?
- Initiate the rollover early. Moving funds from an employer plan or standard brokerage to a self-directed custodian can involve institutional bureaucracy and paperwork delays. Plan for several weeks of transfer time before you need to sign subscription documents.
- Review fee structures. Self-directed custodians typically charge either an asset-based fee or a flat fee per transaction. Review the fee schedule to understand how ongoing maintenance affects your target net yield.
Verifying Accredited Status and Offering Compliance
- Confirm your qualification standard. The SEC requires individuals to meet specific financial standards, such as a net worth over $1,000,000 alone or jointly with a spouse or spousal equivalent, excluding your primary residence. Alternatively, an individual income over $200,000 or joint income over $300,000 in each of the two most recent years with a reasonable expectation of the same level this year qualifies you. For more background on how these assets interact, see Retirement Accounts and Your Accredited Status
- Prepare verification documents. If you are participating in a Rule 506(c) offering where general solicitation is permitted, the issuer must take reasonable steps to verify your accredited status. For more information on this structure, see Can I invest my IRA in a 506(c) deal?
- Check third-party verification options. Under Rule 506(c), verification can be satisfied by written confirmation from a registered broker-dealer, SEC-registered investment adviser, licensed attorney, or CPA. An SEC staff no-action letter from March 2025 also recognizes a high minimum investment of at least $200,000 for natural persons, paid in cash and not financed by a third party, combined with written representations as a reasonable verification method.
- Identify offering exemptions. Private placements generally rely on exemptions such as Rule 506(b) or Rule 506(c). Securities purchased under these exemptions are restricted securities, meaning resale is limited and holding periods usually apply.
Conducting Asset and Partnership Due Diligence
- Assess liquidity constraints. Private equity funds, syndications, and private debt placements are illiquid. Make sure the capital you commit will not be needed for short-term distributions or required minimum distributions.
- Understand the distribution flow. Clarify how returns and preferred returns are distributed, and whether capital returns go directly back to your custodial cash balance. You can review common payout structures using the Preferred Return and Waterfall Calculator.
- Review tax reporting requirements. Private operating partnerships issue Schedule K-1s to report income, deductions, and credits. To prepare for how these forms affect your filing timeline, read Understanding Your K-1 as a Private Investor.
- Check for potential debt tax exposure. If your self-directed account invests in a partnership that uses use, the income generated from that debt may trigger Unrelated Debt-Financed Income (UDFI), leading to tax liabilities inside an otherwise tax-advantaged account.
Executing the Subscription and Funding
- Title documents correctly. The investment must be titled in the name of your custodian for the benefit of your specific account, rather than in your personal name. Incorrect titling can void the tax-advantaged status of the purchase.
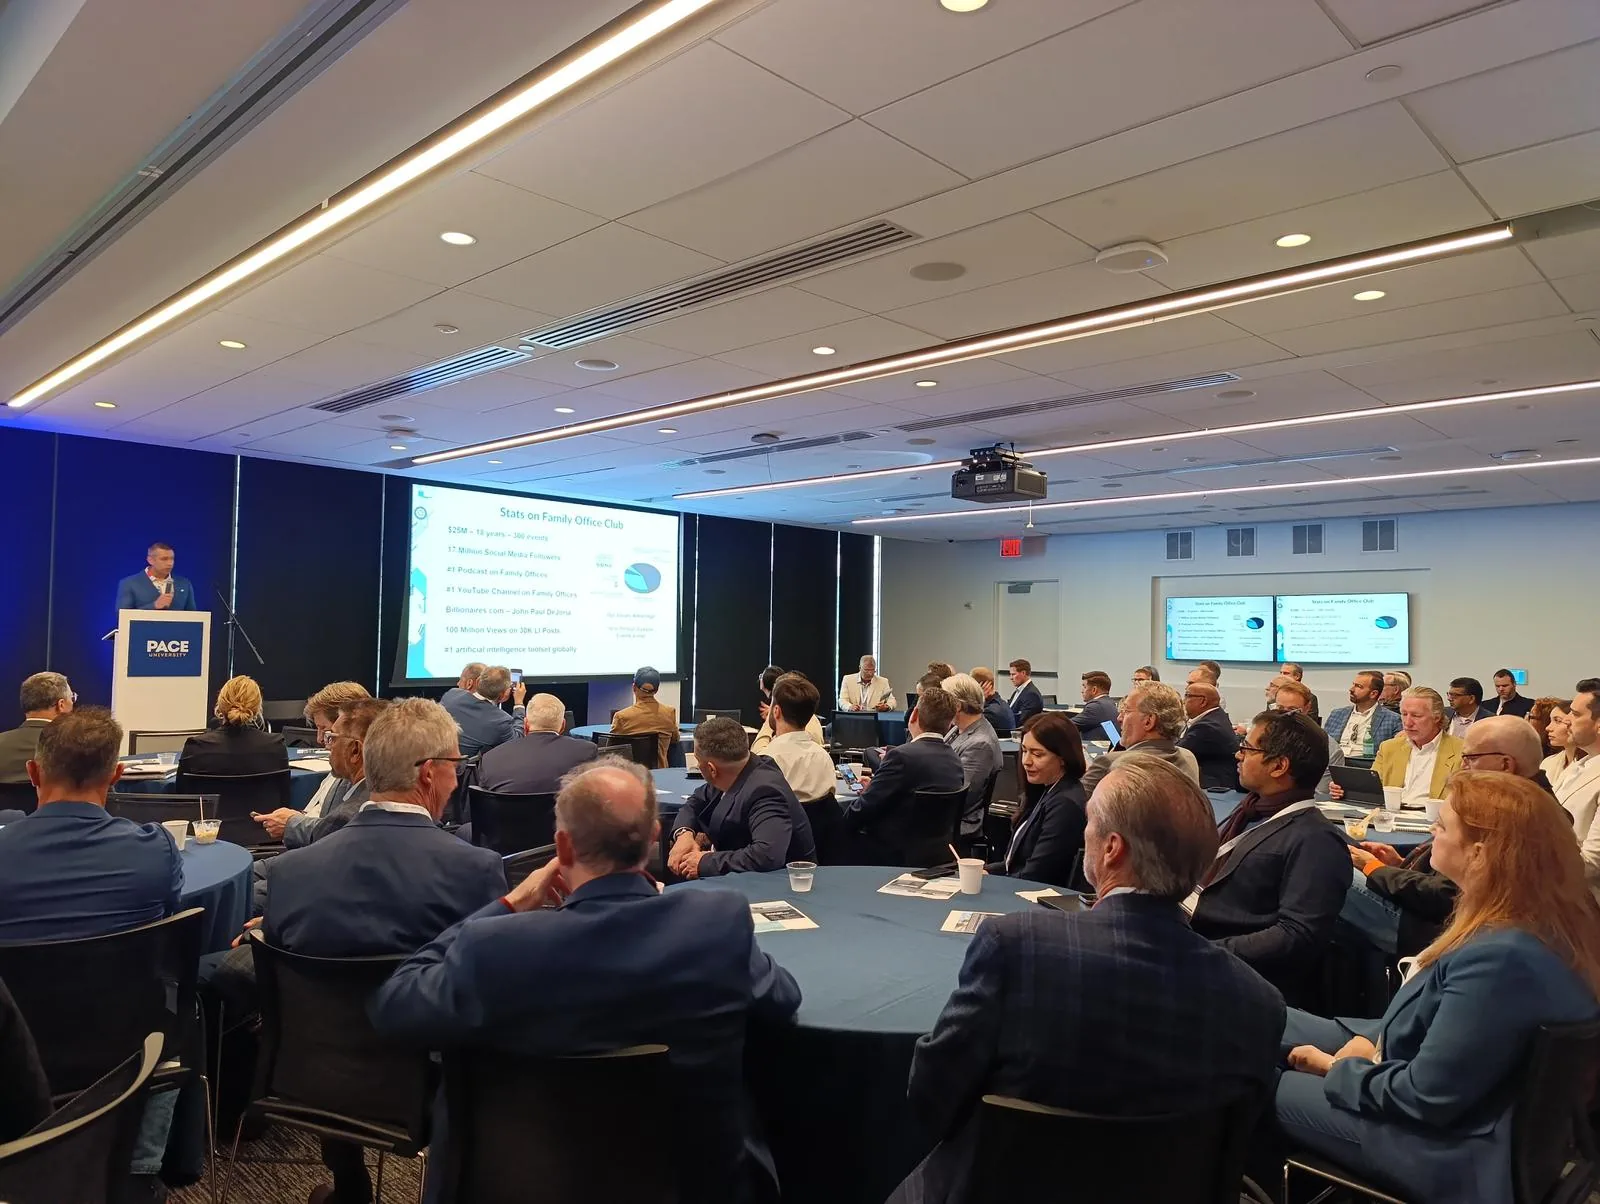
- Route documents through your custodian. At a Family Office Club workshop, Richard C. Wilson explained that private transactions require direct coordination between the deal sponsor and the custodian, because the custodian must sign the final subscription documents on behalf of your account.
- Wire directly from the custodial account. All investment capital must flow directly from the custodial bank account to the issuer, and any future distributions must flow straight back into the custodial account.
- Maintain clear transaction records. Keep digital copies of all signed subscription agreements, operating agreements, and wire receipts for both your personal records and your custodian's annual valuation reporting.
Common mistakes
- Mixing personal and retirement funds. Paying deal expenses with personal cash or transferring funds through a personal checking account is a prohibited transaction that can disqualify the entire account.
- Underestimating custodian processing times. Waiting until a deal's closing deadline to open an account or request a wire often causes missed investment windows.
- Ignoring debt-financed income rules. Many first-time investors forget that used real estate syndications inside an IRA can generate taxable income requiring an annual Form 990-T filing.
- Assuming custodians vet the investment. A speaker at a Family Office Club event pointed out that self-directed custodians only process administrative paperwork and maintain custody, they do not perform due diligence or endorse any deal.
Frequently asked questions
Can my self-directed IRA invest in real estate or private companies?
Yes. Self-directed IRAs can hold private equity, real estate syndications, mortgage notes, private debt, and other alternative assets. The account custodian facilitates the custody and administration of these private assets as long as the transactions follow federal rules.
What is a prohibited transaction in a self-directed IRA?
A prohibited transaction occurs when your retirement account engages in a transaction with a disqualified person, such as yourself, your spouse, your children, or your parents. This includes buying property for personal use, lending money to family members, or providing personal services to an asset owned by the account.
How does using use in a private deal affect my IRA?
When an IRA invests in a partnership or syndication that uses mortgage debt or other financing, the portion of profits attributable to that borrowed capital may be subject to tax. The custodian typically files Form 990-T and pays any tax owed directly out of the IRA cash balance.
Related reading
- Is self-certification enough for a 506(b) deal?
- Private Deal Red Flag Checklist
- How to Evaluate a Private Deal Sponsor
- Private Deal Fees Explained: What You Really Pay
- Private Deal Red Flags Every Investor Can Spot
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club investor event
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC Rule 144 (eCFR)
- SEC EDGAR full-text search
