
Why private investors receive a K-1
Most private funds and syndications are set up as partnerships or LLCs taxed as partnerships. The entity usually does not pay income tax itself. Instead, the results pass through to the owners. Each owner gets a K-1 showing their slice.
This is why a K-1 feels different from a brokerage statement. A 1099 reports what a payer gave you. A K-1 reports your share of what the whole entity did, whether or not the cash reached you. A deal can send you a K-1 in a year when it paid you nothing, and it can show a loss in a year when you collected distributions.
Some investments use other forms of K-1, such as those from S corporations or trusts. The idea is the same.
The parts worth finding first
The form looks busy. You do not need to master every line on day one. Start with these areas:
- Your information. Check your name, address and tax ID. Errors here cause delays later.
- Your ownership percentage. This shows your share of profits, losses and capital. Compare it with your subscription documents.
- Income and loss boxes. These show ordinary business income or loss, rental income or loss, interest, dividends and capital gains. Each flows to a different place on your return.
- Deductions and credits. These can include depreciation passed through to you and other items the sponsor reports.
- Distributions. This box shows cash or property the entity paid out to you. It is not the same thing as income.
- Capital account. This tracks what you put in, what you earned, and what you took out.
- Other information. Footnotes and supplemental pages often explain items that do not fit in a box. Read them.
If you invested through a self-directed IRA, the K-1 can look different in its effect. Some income inside an IRA may be taxable in certain cases, so it helps to know that before you invest.
Why your tax number can differ from your cash
This is the idea that surprises new investors most. In many cases, the income on your K-1 does not match the money you received.
Depreciation is a common reason. Real estate, equipment and other assets lose value on paper over time, and the tax rules let the entity deduct that. The deduction can reduce or even erase taxable income while cash still flows to you. In his training, Richard C. Wilson describes depreciation as one of the biggest allies in building wealth because it can offset cash flow. He calls this tax flow optimization.
The reverse can also happen. An entity can earn taxable income and keep the cash for reinvestment or debt payments. Then you owe tax on money you have not yet received. Some people call this phantom income. It is worth asking about before you invest.
If your deal has a preferred return, the Preferred Return and Waterfall Calculator helps you see how cash is meant to be split. That is a different question from how the K-1 reports taxable income, so keep the two apart in your mind.
When to expect it
Timing is the part of K-1s that frustrates people most. A K-1 cannot be finished until the entity completes its own return. If the underlying business has many assets, partners or states involved, that can take a while.
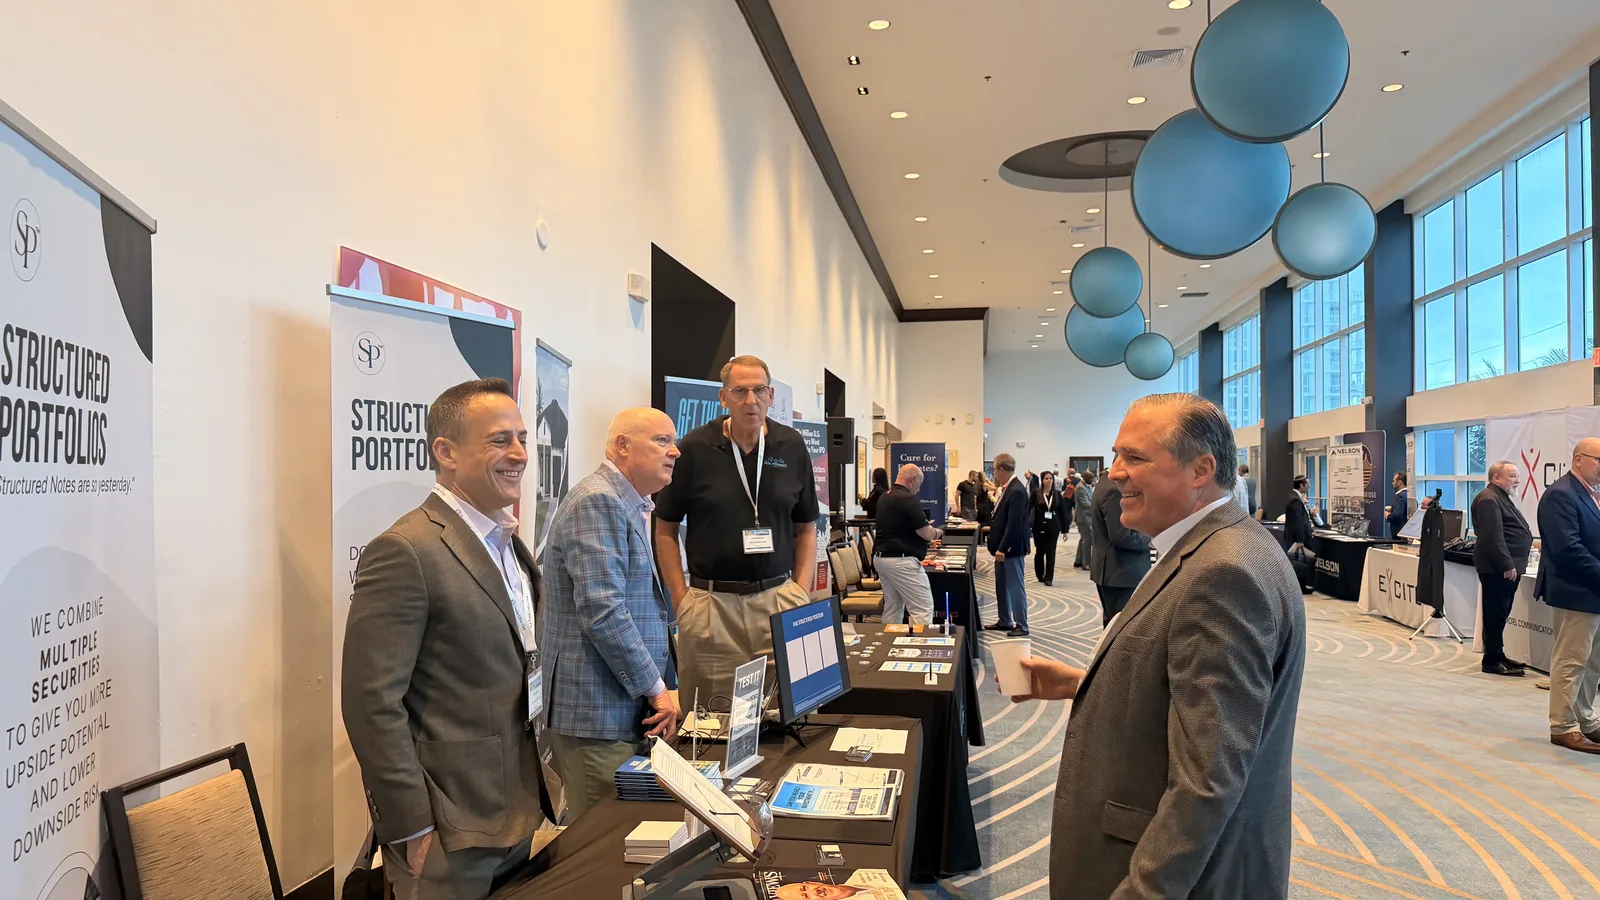
A speaker at a Family Office Club event described a sponsor who delivered K-1s in March every year and noted that others are known for sending them in late summer or fall. That gap is real. Late K-1s can push you to file an extension, and you may need to estimate your tax payments in the meantime.
Before you invest, ask the sponsor three simple questions:
- When do you usually deliver K-1s?
- Do you provide an estimate earlier if the final form is late?
- In how many states will I have a filing requirement?
Our K-1 Tax Season Checklist for Private Investors walks through what to gather and when.
Reading deductions with care
Private deals sometimes advertise large first-year deductions, often from accelerated or bonus depreciation on equipment or from other up-front costs. At one Family Office Club event, investors compared notes on this. They had heard of deals where a large part of the investment was treated as equipment and written off quickly. They also found that tax professionals did not always agree on how it applied to each person.
That is a useful lesson. A deduction on a K-1 is not automatically a deduction you can use. Several rules can limit it, including how much you have at risk, your basis in the investment and whether the activity counts as passive. Your role matters too. Being an active participant in a business is different from being a passive investor.
Another speaker pointed out that tax professionals do not always bring up planning ideas on their own. They tend to answer the question you ask. So come with specific questions about your K-1, such as which deductions are limited and which carry forward.
Treat any pitch that promises a fixed percentage back at tax time with healthy caution. Your result depends on your own income, your state and your situation.
If you are a first-time investor, a medical professional or a retiree
First-time investors. Expect your first K-1 to feel unfamiliar. That is normal. Read the form against the offering documents and compare the ownership percentage and distributions to your own records. Keep every K-1, along with your original investment records. You will need them when the investment ends.
Doctors, dentists and other medical professionals. Your schedule is full, and your income may already put you in a high bracket. A late K-1 can disrupt a filing you wanted done early. Plan for extensions as a normal possibility. Also check which states the investment touches, since income from a deal can create filing duties outside your home state. If you are still building toward accredited status, see How Accredited Investor Verification Works.
Retirees and pre-retirees. Your income may be changing, and your tax picture may rely on fixed income plus withdrawals. A K-1 can add taxable income that is not matched by cash. Think about whether you could pay that tax without selling something else. If you hold private deals inside an IRA, the rules differ from a taxable account, so read the form with that in mind.
A simple yearly routine
- Save the offering documents and your ownership details in one folder.
- Track every distribution you receive during the year.
- When the K-1 arrives, check your details and ownership percentage.
- Compare the distributions box to your own records.
- Read the footnotes and any supplemental pages.
- Note any losses or deductions that may be limited, so you can follow them from year to year.
Do this every year for every deal. It takes a little time and it makes the process much calmer.
Frequently asked questions
Do I owe tax if I received no cash from the investment?
In many cases, yes. The K-1 reports your share of the entity's taxable income, whether or not it paid you anything. That is why it helps to ask a sponsor how they expect taxable income and cash distributions to line up.
What if my K-1 arrives after the filing deadline?
This happens often with private investments. Many investors file an extension and pay an estimated amount by the original deadline. The final K-1 then lets them file an accurate return. Asking the sponsor about their usual timing helps you plan ahead.
Is a K-1 the same as a 1099?
No. A 1099 reports payments made to you. A K-1 reports your share of an entity's results, and that share can be larger or smaller than the cash you received. K-1s also tend to arrive later and can bring state filing questions that a 1099 usually does not.
Related reading
- Do I owe tax on K-1 income I did not receive?
- Income Verification Checklist for Accreditation
- Retiree Income Investments Checklist
- The Accredited Investor Income Test, Explained Simply
- Private Investing for Doctors and Physicians
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Richard C. Wilson capital raising training series
- Family Office Club event
- Family Office Club investor event
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
