
How an IRA fits into a 506(c) offering
Rule 506(c) lets a sponsor advertise publicly. In exchange, every purchaser must be accredited, and the sponsor must take reasonable steps to verify it.
Most standard IRAs at large brokerages can't buy private deals. You usually need a custodian that supports alternative assets, which is what people mean by a self-directed IRA. You direct the investment. The custodian signs the paperwork and holds the account's interest.
Many sponsors look through the account to the person who directs it when they check accredited status. Practices vary, so ask the sponsor early how they treat retirement accounts. Our guide on retirement accounts and your accredited status explains the common approaches.
What verification looks like
Checking a box is not enough for a 506(c) deal. Sponsors commonly use one of these routes:
- IRS forms for the last two years, plus a written statement, to show income.
- Recent asset and liability documents, plus a credit report and a written statement, to show net worth. Your primary residence is excluded as an asset.
- A letter from a registered broker-dealer, an SEC-registered investment adviser, a licensed attorney or a CPA, dated within the prior three months.
- A high minimum investment, at least $200,000 for an individual, paid in cash and not financed by a third party, plus written statements. SEC staff have said this can be a reasonable step.
Our page on how accredited investor verification works walks through each method.
What experienced IRA investors look for
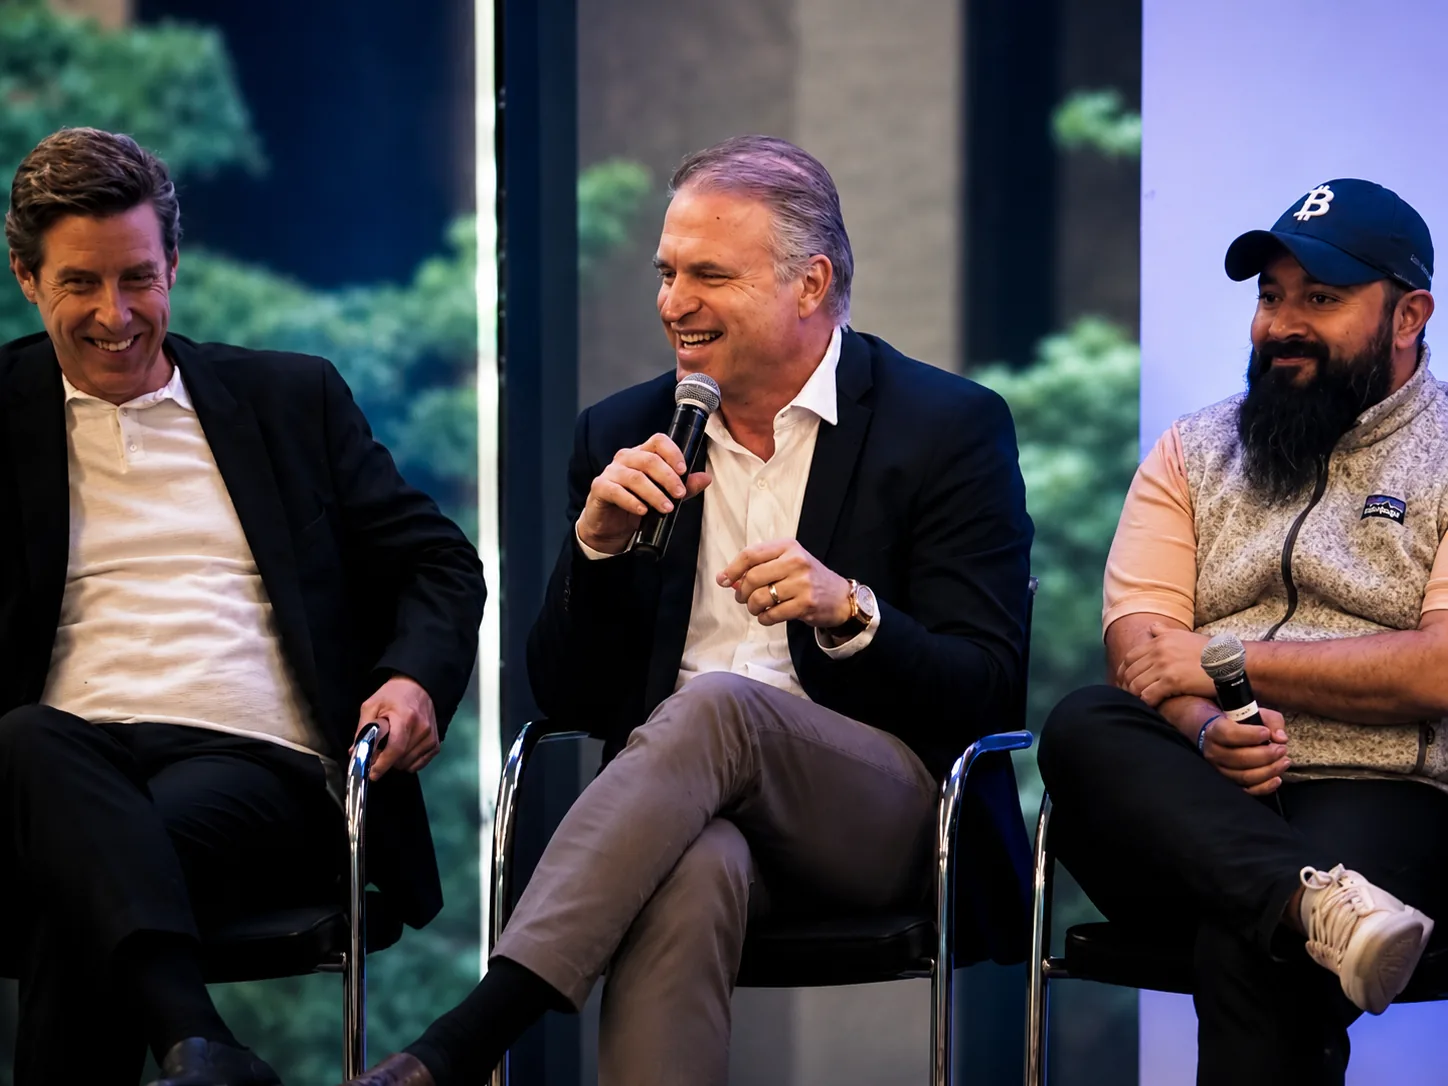
A speaker at a Family Office Club event described investing through a self-directed Roth account in private placements, both 506(c) and 506(b). Most were standard growth and income deals such as apartment projects. They kept their role fully passive.
Two habits stood out:
- They wanted a preferred return of at least eight percent. They didn't need the cash. They saw it as proof the property was producing income.
- They preferred to see some distributions along the way, rather than hearing that returns would come after several years.
Another speaker pointed out that your custodian will, at some point, ask for a fair market value of what the account holds. A third-party appraisal may be needed. Ask the sponsor how valuations will be handled and who pays for them.
Before you send money
Run through the basics first:
- Confirm your custodian accepts this type of investment and ask about its fees and timing.
- Remember that Rule 506 securities are restricted. Resale usually needs an exemption, and holding periods apply. Treat the money as locked up.
- Sponsors must file a Form D within 15 days after the first sale, and bad actor rules apply to the offering. Ask to see how the sponsor handles both.
- Use the Self-Directed IRA Private Deal Checklist to keep your questions in order.
If your account is a Roth, a few details differ. See Can I use a Roth IRA for private deals?
Frequently asked questions
Is a 506(b) deal different for an IRA?
A 506(b) offering can't use general solicitation. It allows unlimited accredited investors and up to 35 non-accredited purchasers who are sophisticated. Sponsors often rely on a reasonable belief that you are accredited rather than formal verification. The custodian steps are usually the same.
Can I sell my interest if I need cash?
Usually not easily. Rule 506 securities are restricted, and there is rarely a public market. Many deals run for several years. Plan on the money staying invested, and remember that an IRA also has its own distribution rules.
Does the sponsor have to tell the government about the deal?
Yes. The sponsor files a notice on Form D with the SEC within 15 days after the first sale. Because Rule 506 offerings are covered securities, states may require notice filings and fees. They can't review the merits of the deal.
Related reading
- Can my spouse and I invest jointly in a private deal?
- Is self-certification enough for a 506(b) deal?
- What documents will I sign when I invest in a private deal?
- Accredited Investor Verification Documents Checklist
- Income Verification Checklist for Accreditation
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club investor event
- Family Office Club webinar
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC EDGAR full-text search
