
How evergreen fund structures work
Traditional private equity and real estate vehicles operate on a fixed schedule. They raise money during an initial period, call capital over three to five years, harvest the investments, and return all proceeds to investors before shutting down.
Evergreen private funds remove this fixed end date. The fund manager operates an ongoing portfolio that continuously buys, manages, and occasionally sells underlying assets. When an asset generates cash flow or sells for a gain, the manager can recycle that capital into new investments rather than distributing everything and closing the fund.
Capital entry and valuation happen on a regular schedule. Managers calculate a Net Asset Value (NAV) on a monthly, quarterly, or annual basis. When you invest, your purchase price reflects this periodic NAV. This structure allows the fund to welcome new participants while continuing to hold seasoned assets.
Capital recycling and long term compounding
A core feature of an open-ended vehicle is the ability to reinvest proceeds. In a traditional private fund, once an asset is sold, the capital goes back to you. You then must find another place to deploy those funds, which can create cash drag and tax events.
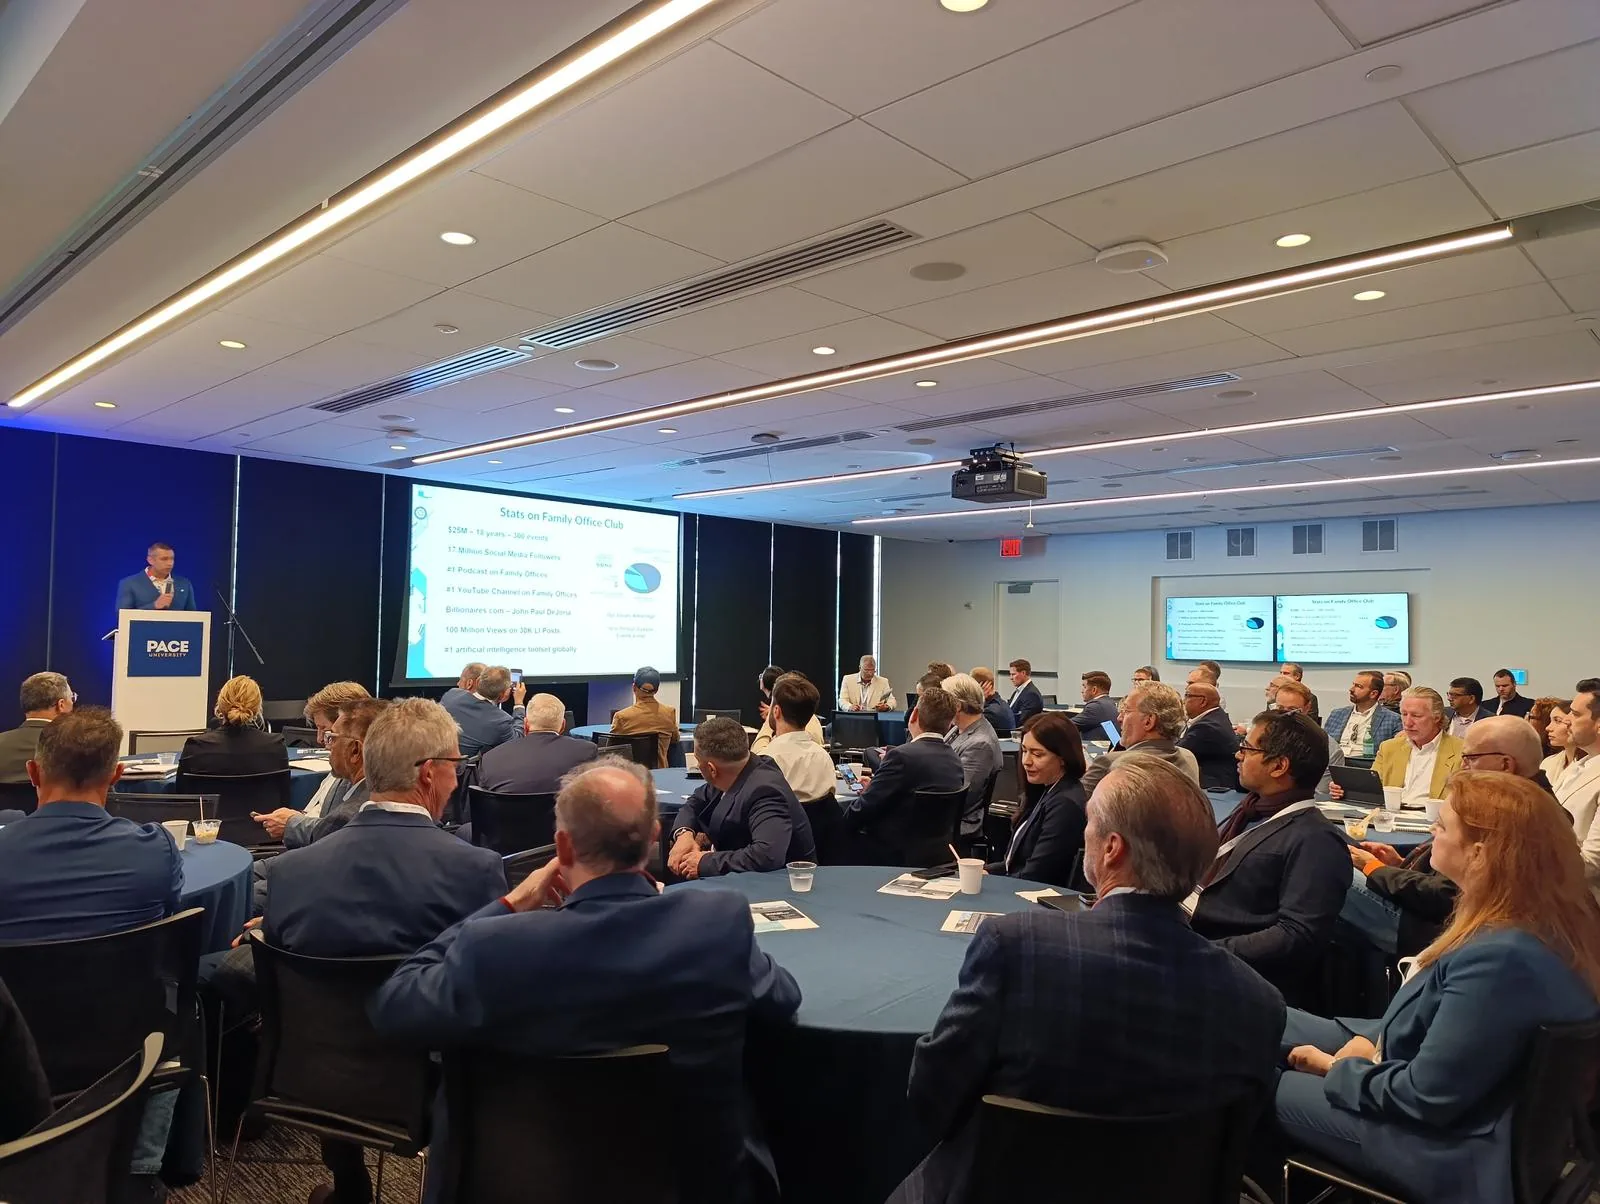
At a Family Office Club event, a speaker explained that evergreen structures allow sponsors to return capital through recaps or dividends while keeping investors in the deal for decades. Once your initial principal and hurdle are covered, your remaining equity can stay invested, compounding value over many years. In his book, Richard C. Wilson writes that building assets with long-term durability creates enduring value that does not need to be rebuilt every few years. The evergreen fund applies this philosophy directly to private markets by letting investments mature without artificial deadlines to sell.
Liquidity mechanics and redemption gates
While evergreen funds are open-ended, they are not liquid like publicly traded stocks. The underlying assets, such as commercial property, private loans, or private equity stakes, take time to sell.
To balance ongoing investments with investor liquidity, evergreen structures use specific redemption terms:
- Notice periods: You usually must notify the manager 30 to 90 days before a designated redemption date.
- Redemption frequency: Redemptions typically occur quarterly or semi-annually.
- Fund-level gates: Managers limit total redemptions to a fixed percentage of the fund NAV per quarter, often between 2% and 5%.
- Lock-up periods: Many funds require a minimum holding period, such as one to three years, before you can request a redemption.
If redemption requests exceed the quarterly cap, distributions are paid pro-rata, and remaining requests carry forward to the next period. Similar mechanisms appear in registered open-ended formats, as covered in our guide to Interval Funds and Tender Offer Funds.
Fees and valuation in open-ended vehicles
Fee structures in open-ended vehicles differ slightly from standard private offerings. In a traditional drawdown fund, management fees are often assessed on committed capital and later on invested capital. In an evergreen fund, the management fee is generally charged against the active Net Asset Value.
Performance incentives also require careful review. Under federal rules, an SEC-registered investment adviser charging a performance fee must ensure clients meet the qualified client standard, which requires at least $1,400,000 under management with the adviser or a net worth above $2,700,000 excluding the primary home.
Managers calculate performance fees based on NAV increases or distributed cash flow above a preferred return. You can learn more about how baseline returns work in our overview of Preferred Returns and Hurdle Rates Made Simple. Understanding total manager compensation is critical, as detailed in Private Deal Fees Explained: What You Really Pay.
Evaluating evergreen funds across investor situations
Evergreen vehicles offer distinct trade-offs depending on your portfolio goals and background:
- Retirees and pre-retirees: Open-ended income funds can provide steady, distributions without requiring you to hunt for a new deal every few years. However, you must keep enough liquid reserves outside the fund to handle living expenses, because redemption gates can delay cash withdrawals during market downturns.
- Seasoned investors: Experienced investors often use evergreen vehicles for asset classes that benefit from patient ownership, such as infrastructure, farmland, or core real estate. The fund manager does not have to exit quality assets simply because a ten-year fund life has expired.
- First-time accredited investors: If you recently crossed the net worth threshold of $1,000,000 (alone or with a spouse or spousal equivalent, excluding your primary residence) or the income mark of $200,000 individual or $300,000 joint in each of the last two years, with a reasonable expectation of the same level this year, open-ended funds offer an easier entry point. You avoid managing complex capital call notices across multiple years and can review an established, active portfolio on day one.
Key risks and red flags to monitor
Operating an ongoing private fund presents operational challenges that closed-end structures avoid. When reviewing an evergreen fund, pay attention to the following areas:
- Valuation policies: Because new investors enter and exiting investors leave based on NAV, fund appraisals must be objective. Independent third-party valuation firms provide better oversight than internal sponsor estimates alone.
- Cash drag vs. liquidity risk: The manager must maintain enough cash or credit lines to honor redemptions without keeping so much cash idle that overall returns drop.
- Mismatched terms: Be cautious if a manager offers quarterly liquidity on highly illiquid development projects. Reviewing fund governance helps protect your capital, as discussed in Private Deal Red Flags Every Investor Can Spot.
Frequently asked questions
What is the main difference between an evergreen fund and a traditional private equity fund?
A traditional private equity fund has a fixed life of around 10 years, collects capital once, and liquidates all assets before closing. An evergreen fund has no termination date, accepts new capital on an ongoing basis, and continuously recycles realized gains into new investments.
How do I get my money out of an evergreen fund?
You submit a redemption request during specified windows, usually quarterly or semi-annually, subject to advance notice requirements. Redemptions are typically capped at a fund-level limit, such as 5% of total NAV per quarter, to protect the portfolio from forced asset sales.
Are evergreen private funds available to all accredited investors?
Most private evergreen funds are offered under Regulation D Rule 506(b) or Rule 506(c), which require investors to meet the standard accredited investor thresholds. However, if the fund manager charges a performance-based fee, individual investors must also qualify as a qualified client with a net worth over $2,700,000 or at least $1,400,000 invested with that adviser.
Related reading
- How Private Funds Work for Limited Partners
- What does a lock-up period mean in a private fund?
- Before You Wire Funds Checklist
- 3(c)(1) vs 3(c)(7) Funds: What It Means for You
- Co-Investments Alongside Funds and Sponsors
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- The Marketer's Bible by Richard C. Wilson
- Family Office Club investor event
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC Rule 205-3, qualified client (eCFR)
- SEC Rule 2a51-1, qualified purchaser investments (eCFR)
