
1. Conduct an on-site visit to inspect their actual operations
Relying only on phone calls or emails is a costly mistake that increases the risk of misrepresentation. Visiting a sponsor's primary office allows you to confirm that a real, professional team exists rather than two individuals working from a temporary desk. Meeting the principals face to face gives you direct visibility into their working environment and organizational culture.
2. Look beyond a basic background check
Standard background checks only tell you if someone has committed serious crimes or past fraud. You must evaluate deeper character traits, integrity, and daily judgment that never appear on a public record. Use a thorough Sponsor Background Checklist to guide your review of their professional reputation and history across the industry.
3. Verify the complete track record across market cycles
Ask for full realized deal histories rather than selected case studies or aggregate metrics. Learn the steps for Verifying a Sponsor's Track Record so you can examine how prior assets performed during downturns, rising interest rate environments, and unexpected operating setbacks. A sponsor who managed challenges transparently is often more reliable than one who only highlights easy wins in bull markets.
4. Run detailed reference calls with past investors and partners
Direct conversations with former equity partners, lenders, and service providers reveal how a manager treats capital when projects face trouble. Following the steps in How to Run Sponsor Reference Calls helps you uncover whether distributions arrived on time, financial reporting remained accurate, and the team communicated bad news promptly. Make sure to source your own references beyond the curated names in the presentation.
5. Review SEC filings and regulatory disclosures
Private offerings under Regulation D require an issuer to file a notice with the SEC on Form D within 15 days after their first sale of securities. Reading Form D for Investors: What It Tells You helps you check stated offering amounts, broker compensation, and participating executives against the private placement memorandum. You should also confirm that no bad actor disqualifications apply under Rule 506(d).
6. Review thought leadership and published materials
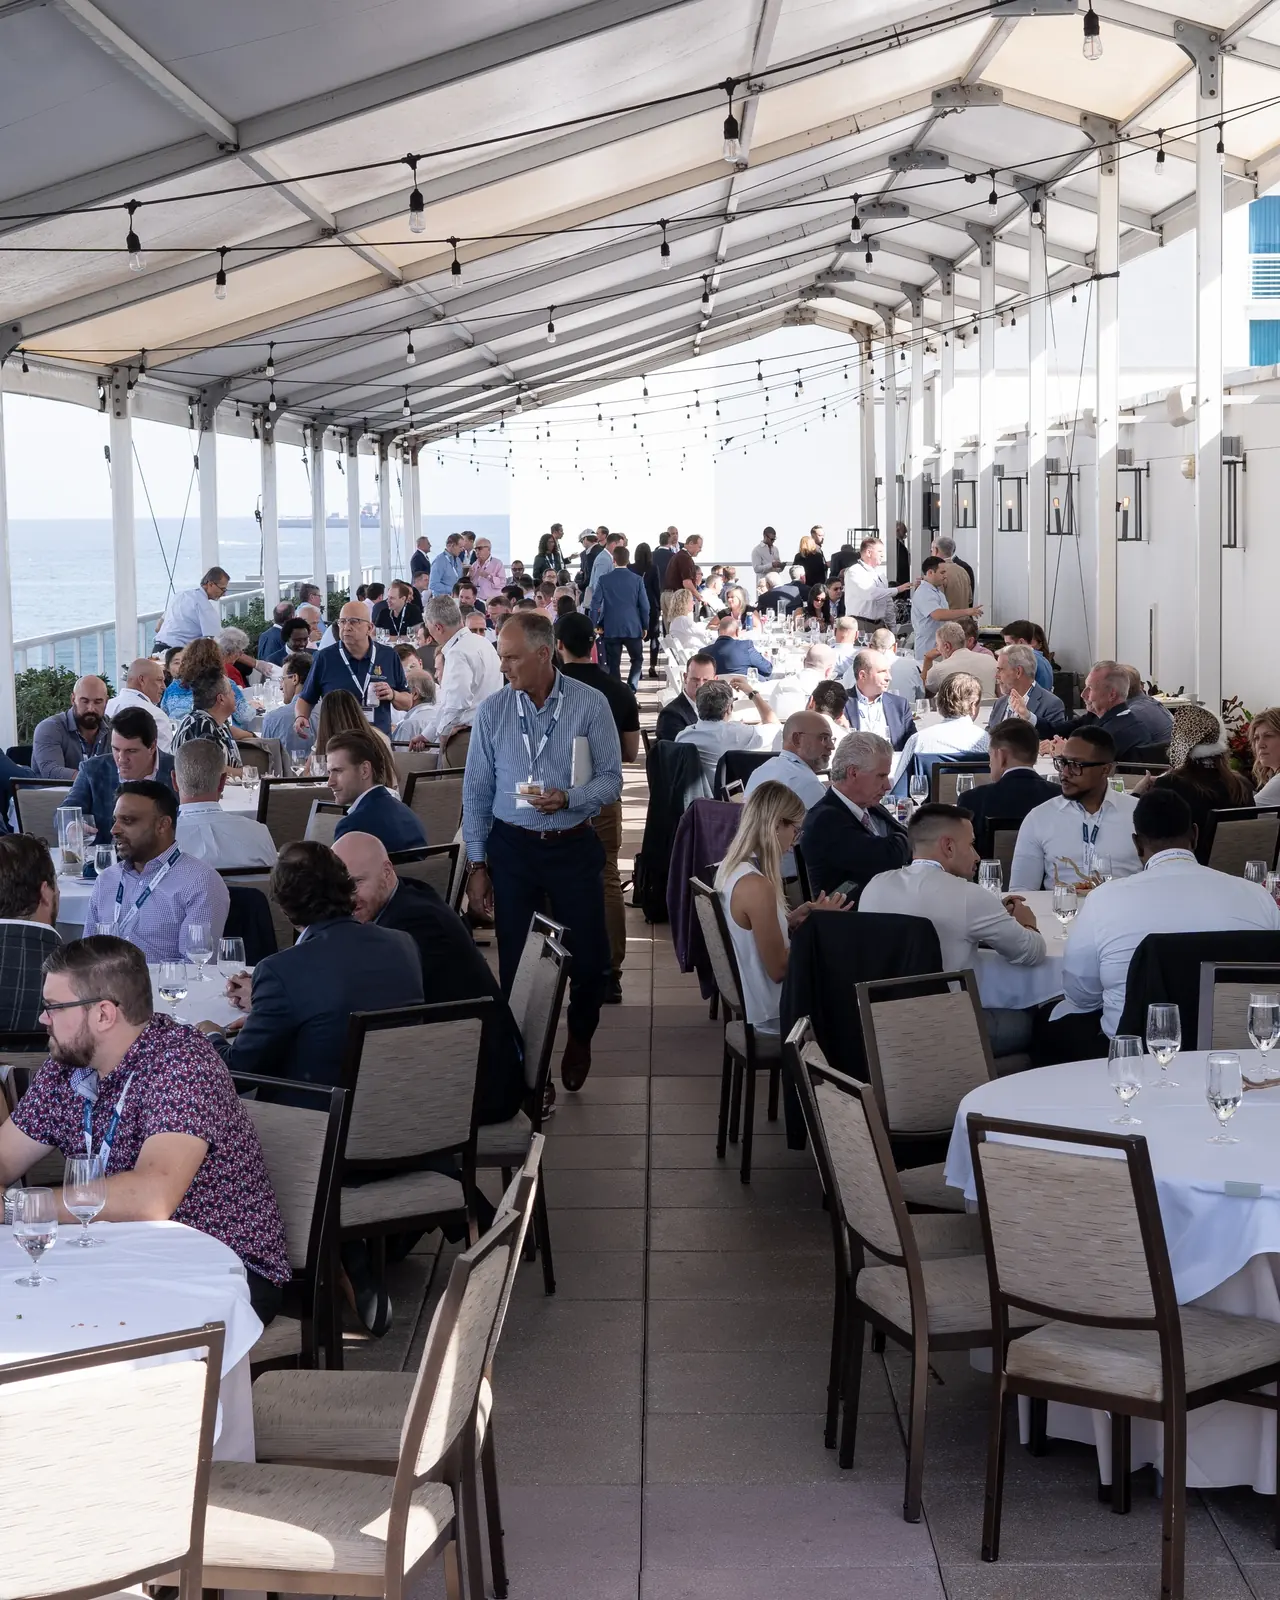
A speaker at a Family Office Club event pointed out that researching a manager's educational content, videos, and articles helps you evaluate their true values and depth of knowledge. Watching how they explain complex deals reveals whether their focus is on long-term relationships or short-term transactions. If their public material seems shallow or unusual, take that as a clear signal to pause.
7. Evaluate the depth and stability of the internal team
Examine who actually sources assets, oversees operations, handles construction or tenant management, and runs investor accounting. If a firm depends entirely on one founder without capable deputies, operational risk rises significantly. Verify how long core team members have worked together and ensure key decision-makers have direct domain experience in the target asset class.
8. Confirm direct alignment through meaningful co-investment
Sponsors should invest meaningful cash equity alongside limited partners into the specific project. Pure sweat equity or recycled acquisition fees do not create the same level of downside risk as actual capital. When a sponsor risks their own capital on the same terms as you, their incentives align directly with preserving principal and maximizing distributions.
9. Analyze fee structures and waterfall incentives
Review acquisition fees, asset management fees, disposition fees, and promoted interest hurdles inside the operating agreement. High upfront fees allow a manager to profit before the asset generates any operational income or value. Healthy structures prioritize a preferred return to investors before the sponsor receives their share of profits.
10. Assess reporting standards and communication cadence
Clear, timely reporting is essential for tracking private investments that lack daily market pricing. Ask for sample quarterly reports, audited annual financials, and investor tax packages from past years to see their standard format. A transparent sponsor provides regular updates on key performance indicators, capital expenditures, and budget variances without requiring constant follow-up.
Frequently asked questions
What is the most critical factor when choosing a deal sponsor?
Integrity and operational experience are the most important elements. Market conditions change, but a sponsor with high character and deep sector knowledge will protect your capital, communicate openly during downturns, and resolve project challenges effectively.
How much personal capital should a sponsor invest in their own deal?
While amounts vary based on the total offering size, a meaningful commitment of cash equity shows true alignment. Many investors look for sponsors to contribute at least two to ten percent of the required equity, ensuring they share the same financial risks as their limited partners.
How do I check if a sponsor has faced regulatory actions?
You can search SEC databases, state securities regulator records, and standard background screening services. Offerings conducted under Rule 506 are subject to bad actor disqualification rules that bar individuals with specific past securities violations from participating.
Related reading
- How to Evaluate a Private Deal Sponsor
- How do I know if a sponsor is legitimate?
- Co-Investment Evaluation Checklist
- Your First Private Deal Checklist
- 10 Tips for Building Sponsor Relationships
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Private Equity, a book by Richard C. Wilson
- Family Office Club library reference text
- Family Office Club event
- The Single Family Office, a book by Richard C. Wilson
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC EDGAR full-text search
