
Gather your records
Prior tax returns. Keep the last two years of returns handy. They can help you compare what changed and answer questions about how an investment was reported before.
Investment documents. Collect subscription agreements, capital account statements, distribution notices and any tax information sent by the fund or business. These records can help you connect a K-1 to the investment it covers.
A list of investments. Write down each private investment, its contact information and whether you expect a K-1. Include investments held through entities or trusts so none are overlooked.
A secure folder. Store tax documents in one place, whether that is a physical folder or a secure digital system. If you have several investments, a simple tracker can show which documents have arrived.
Review each K-1
Check the names and details. Confirm that the K-1 has your correct name, taxpayer identification details and ownership information. Contact the issuer if something appears wrong.
Match it to the investment. Compare the fund or business name and tax year with your records. If you do not recognize a K-1, find out what investment it relates to before setting it aside.
Note the reported items. K-1s can report income, losses, deductions and other tax items. The form may show amounts even when you received no cash distribution. For a plain-language overview, see Understanding Your K-1 as a Private Investor.
Keep supporting statements. Some K-1s include supplemental schedules or state-specific details. Save those pages with the form because they may explain how an amount was calculated or where it applies.
Track missing or updated forms
Mark what has arrived. Update your tracker when a K-1 comes in, including the date received and whether supplemental pages were included. This makes it easier to follow up on anything still missing.
Ask about timing. If you have not received a K-1, contact the issuer to ask when it expects to send one. Private investments may have different reporting schedules, so keep a note of the response.
Save corrected forms. If an issuer sends an amended K-1, keep it with the original and clearly mark which one is current. Tell the person preparing your return that a correction arrived.
Review state information. A K-1 may include state reporting details that differ from what you expected. Keep those details with your records so they are not missed when your return is prepared.
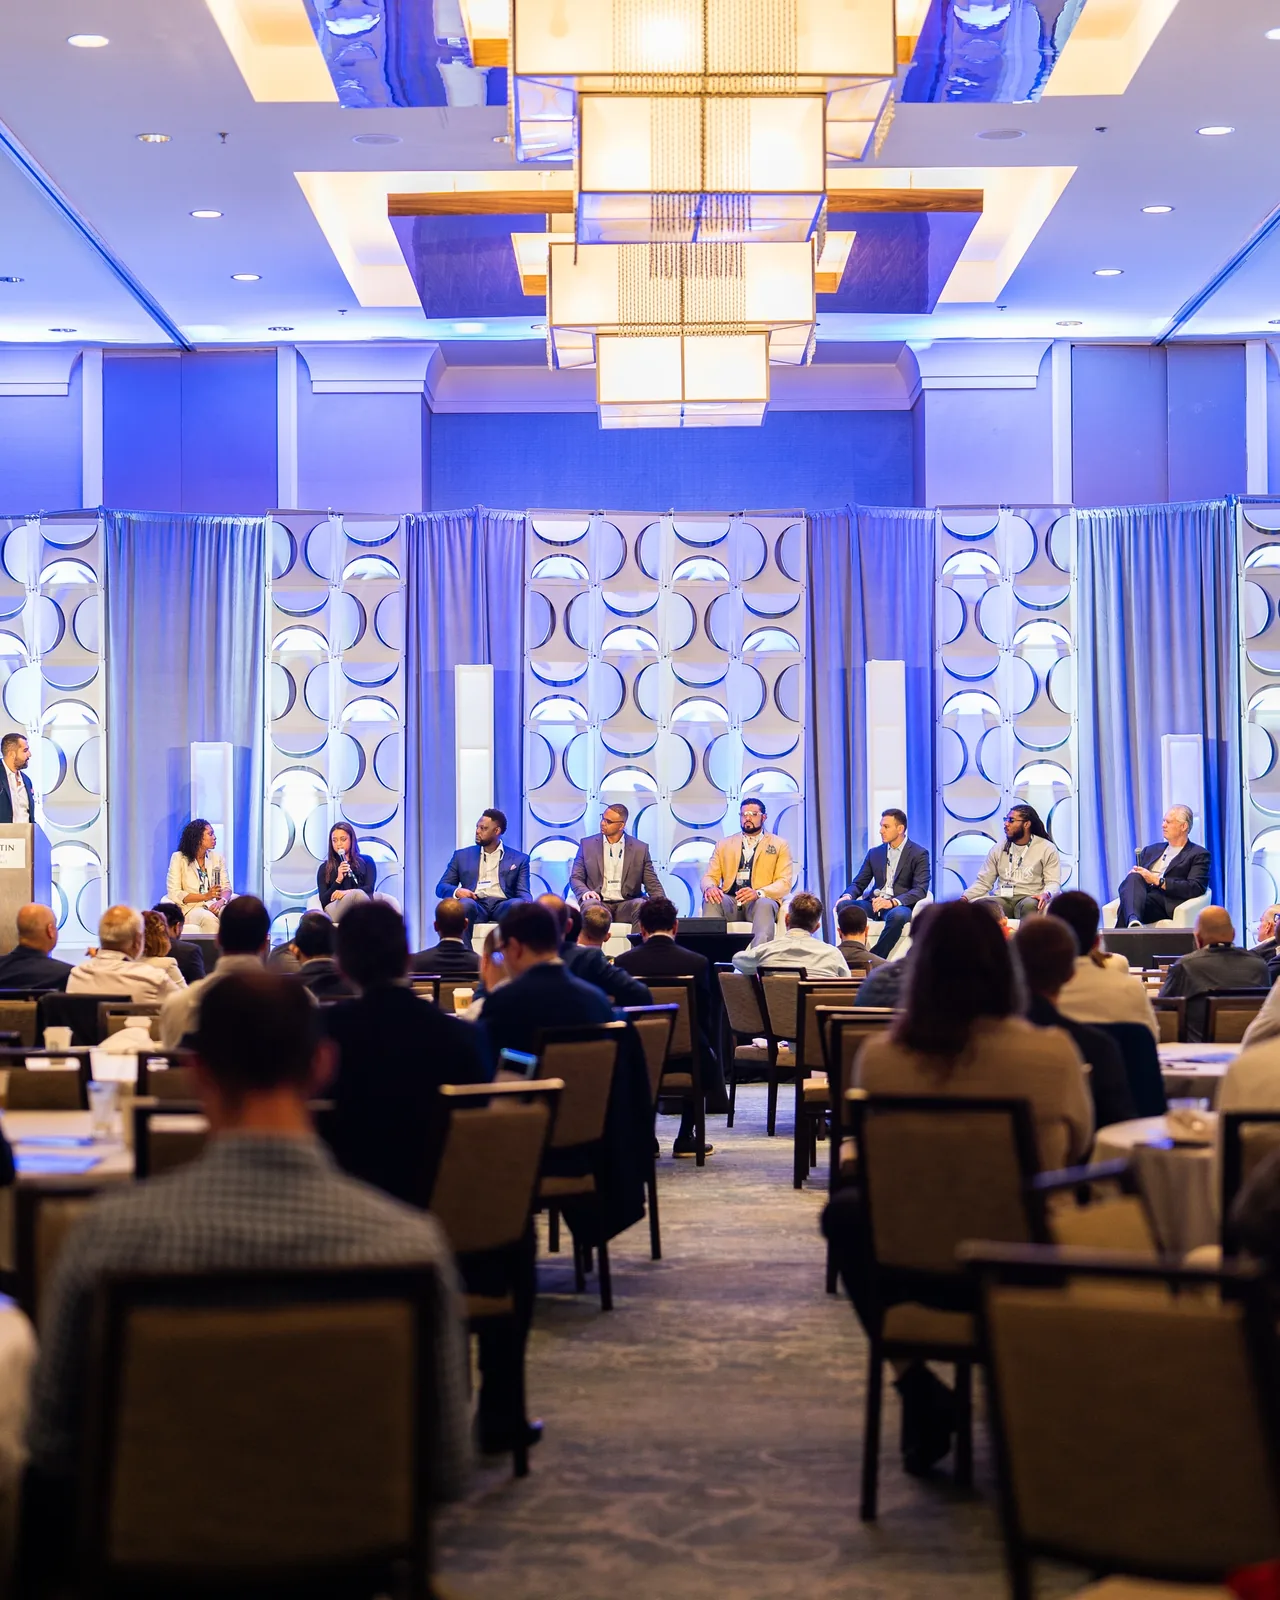
At a Family Office Club workshop, Richard C. Wilson described asking what happened when an investment went sideways and how an operator handled difficult periods. That habit of asking about problems, not just good outcomes, also helps you keep useful records when an investment has a complicated tax year.
Prepare your questions
Write down unusual items. Note any amount, label or change you do not understand. A short list makes it easier to get clear answers about the form.
Ask about changes from last year. If a K-1 reports something different from prior years, ask the issuer whether the investment, ownership or reporting changed. Keep the answer with your documents.
Include cash activity. Record contributions and distributions separately from the K-1 amounts. Cash received and taxable items reported on the form are not always the same.
Use a repeatable routine. The 8 Tips for a Calmer K-1 Tax Season offers more ideas for keeping forms and follow-ups organized.
Common mistakes
Assuming no cash means no tax information. A K-1 can report tax items even when you received no distribution. Review the form and its attachments.
Filing away an incomplete package. Check for supplemental pages and state details before marking a K-1 complete.
Forgetting an investment. Compare the forms received with your investment list. Follow up on investments that may issue a K-1 but have not sent one.
Keeping an outdated version. If you receive an amended K-1, make sure the corrected form is the one used to prepare your return.
Frequently asked questions
What is a K-1?
A Schedule K-1 reports your share of certain tax items from a partnership, S corporation, trust or estate. The issuer provides it to you for use in preparing your tax return.
Why might I receive a K-1 after other tax forms?
Private investments may need time to gather information and prepare their tax reporting. Ask the issuer about its expected timing and track any forms that are still outstanding.
What should I do if a K-1 looks wrong?
Write down what seems incorrect and contact the issuer to ask for an explanation or correction. Keep any response and corrected form with your tax records.
Related reading
- Why do 506(c) sponsors ask for my tax returns?
- Accredited Investor Verification Documents Checklist
- Entity Accredited Status Checklist
- Estate Planning for Private Holdings Checklist
- Onboarding With a Family Office Checklist
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- The Single Family Office, a book by Richard C. Wilson
- Richard C. Wilson capital raising training series
- Family Office Club library reference text
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
