
1. Focus on total portfolio risk rather than single deals
In his book on portfolio fundamentals, Richard C. Wilson writes that risk and expected return must be treated as coequal factors across your entire portfolio. An investor might find several individual deals attractive, but stacking similar assets can concentrate risk in ways that hurt you later. True balance comes from selecting opportunities that complement one another rather than evaluating each deal in total isolation. Learn more about pacing this process in our guide on Building a Private Portfolio Over Time.
2. Respect the cost of illiquidity
Private market investments lack the daily liquidity of public equities or Treasury bills. In his book, Richard C. Wilson highlights that liquidity is defined by how fast an asset converts to cash without hurting its price, contrasting liquid Treasuries with illiquid physical real estate. Rule 506 private securities are restricted securities under federal rules, meaning holding periods apply and quick sales are rarely possible. Only allocate capital to private offerings that you can comfortably commit for five to ten years or longer.
3. Diversify across geographic markets and property types
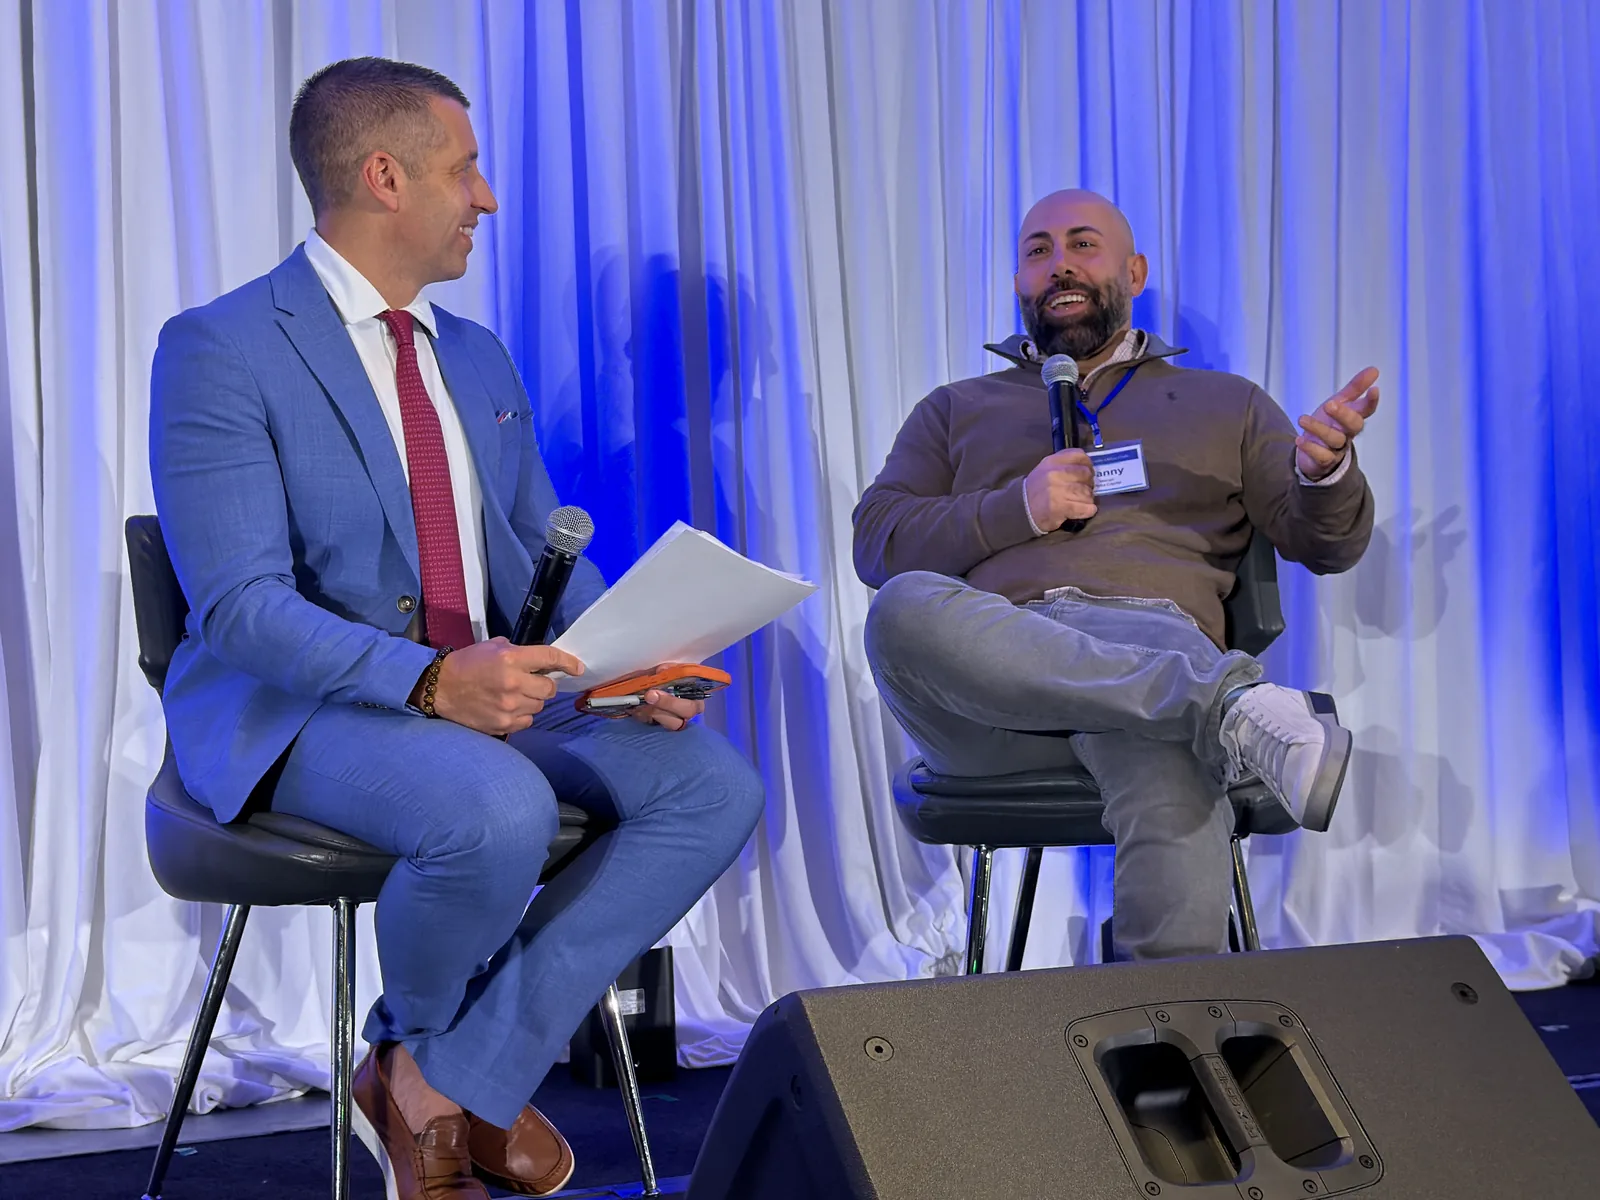
Spreading capital across multiple regions protects your holdings from local downturns, regulatory changes, or zoning constraints. A speaker at a Family Office Club event explained that when reviewing real estate, they look across distinct regional markets while targeting specific local advantages like transport corridors and natural barriers to entry. Mixing geographic areas and asset sub-types helps prevent a single regional slump from damaging your broader returns.
4. Keep dry powder ready for market shifts
Market cycles naturally create moments where transaction velocity drops and pricing resets between buyers and sellers. A speaker at a Family Office Club event shared that keeping capital in reserve allows you to remain patient until opportunities offer appropriate risk-adjusted returns. Forcing money into crowded or overpriced deals often hurts performance, while holding cash gives you the flexibility to invest when valuations turn favorable.
5. Vet deal sponsors thoroughly before reviewing terms
The capability, character, and track record of the sponsor matter as much as the underwriting numbers on a spreadsheet. Attend investor gatherings to meet managers face to face and watch how they answer direct questions about past losses and downside protection. For practical advice on establishing these relationships, review our resource on Meeting Sponsors and Fund Managers at Events.
6. Verify your accreditation status in advance
Private offerings under Regulation D rely on specific federal standards. For instance, the individual net worth test requires over $1,000,000 alone or jointly with a spouse or spousal equivalent, excluding the value of your primary residence, while the income test requires over $200,000 individually or $300,000 jointly in each of the two most recent years, with a reasonable expectation of reaching the same level in the current year. Because issuers under Rule 506(c) must take reasonable steps to verify your status using tax forms, asset statements, or third-party letters, having your documentation organized speeds up your access to deals.
7. Ask detailed questions about debt and fee structures
Sponsors use different financing models, from conservative low-debt structures to aggressive floating-rate loans that increase vulnerability during downturns. Before allocating funds, ask the manager how their debt is structured, when it matures, and how their management fees and carried interest align with investor outcomes. You can prepare for these discussions with our guide on 15 Tips for Asking Sponsors Better Questions.
8. Build a network for continuous deal flow
High-quality private opportunities rarely advertise on public channels. Participating in investor communities, attending workshops, and speaking with other family offices helps you learn about off-market deals and gain insights on operating partners. Richard C. Wilson emphasizes that actively participating in specialized industry events helps private investors build the long-term professional relationships required to source deals and talent.
9. Match your asset allocation to your personal timeline
Asset allocation is the process of dividing capital among equities, fixed income, real estate, and cash to withstand unexpected market disasters. Your ideal mix depends on your stage in life, ongoing cash flow needs, and overall capacity for risk. Constructing an allocation with uncorrelated private assets allows your portfolio to maintain stability even during broader market disruptions.
10. Understand the offering rules governing your investment
Private placements generally follow specific regulatory paths, such as Rule 506(b) or Rule 506(c). Under Rule 506(b), sponsors cannot use general solicitation, while Rule 506(c) permits public advertising but requires rigorous verification of accredited status. Knowing how a deal is structured ensures you understand the disclosures you will receive, the background checks performed, and the verification documents you must provide.
Frequently asked questions
How much of my net worth should be placed in private investments?
The exact percentage depends on your personal financial goals, time horizon, and liquidity needs. Many accredited investors begin with a modest allocation of 5% to 15% in private assets while keeping the remainder in liquid public markets or cash reserves. Because private securities cannot be sold quickly, you should only commit funds that you will not need for short-term living expenses or emergency liquidity.
What is the difference between an individual deal and a private fund?
An individual deal, also known as a direct investment or co-investment, places your capital into a single asset, such as one commercial building or one operating company. A private fund pools capital from multiple investors to acquire a diversified portfolio of assets managed by the general partner. Direct deals give you complete control over which assets you own, while funds provide automatic diversification across several properties or companies within a single commitment.
How do federal rules verify that I am an accredited investor?
For offerings conducted under Rule 506(c), the issuer must take reasonable steps to verify your accredited status rather than simply accepting a check-the-box form. This can be accomplished by submitting IRS forms showing qualifying income for the prior two years, providing balance sheet documents and credit reports dated within the last three months, or obtaining a written verification letter from a licensed CPA, attorney, registered broker-dealer, or investment adviser.
Related reading
- Pacing Your Commitments in a Private Portfolio
- Retiree Income Investments Checklist
- Angel Investing for Accredited Investors
- Co-Investments Alongside Funds and Sponsors
- New Money First Steps Into Private Investing
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club investor event
- Family Office Club library reference text
- How to Start a Family Office mini-series
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC Rule 144 (eCFR)
