
How a preferred return works in practice
In private equity, real estate syndications, and private debt funds, distributions follow a set schedule. If a project has an 8 percent preferred return, the property or operating business must generate enough profit to pay investors that 8 percent hurdle before the sponsor takes a share of the upside.
If an asset underperforms or encounters unexpected expenses, actual cash flow may fall short. In that scenario, investors might receive a smaller distribution or nothing at all for that period. You can test how different cash flows alter investor payouts with our Preferred Return and Waterfall Calculator.
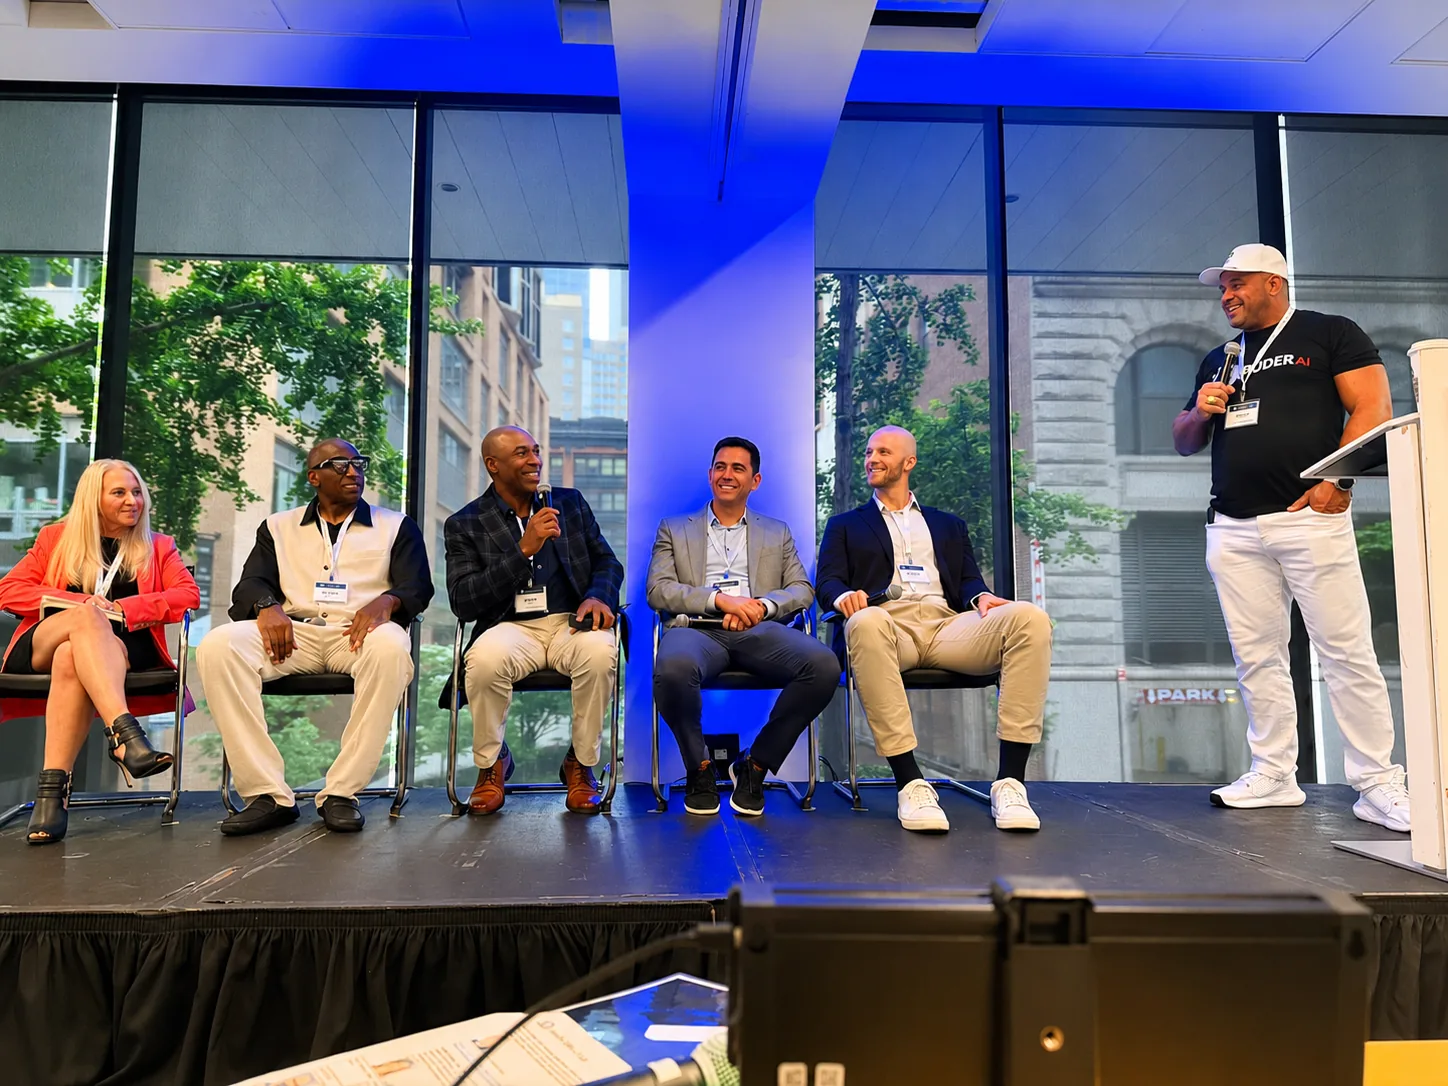
As a speaker at a Family Office Club event explained, a preferred return is a target and a mechanism for alignment, not an absolute promise. It aligns interests by holding back the sponsor's performance reward until the investors meet their baseline return.
Cumulative versus non-cumulative hurdles
The legal documents of the offering dictate what happens when an investment cannot pay its preferred rate in a given year.
- Cumulative preferred returns: Unpaid amounts roll over and accumulate into future quarters or years. The full unpaid balance must be satisfied before the sponsor collects performance fees later on.
- Non-cumulative preferred returns: If the deal generates insufficient cash in year one, that shortfall disappears. The next year starts fresh with no catch-up for past missed targets.
For a deeper look at hurdle mechanics and catch-up clauses, read our guide on Preferred Returns and Hurdle Rates Made Simple.
Sponsor character and downside protection
A preferred return cannot fix a broken business model or protect capital from an unreliable team. At a Family Office Club mastermind, Richard C. Wilson explained that you cannot do a good deal with a bad person. Knowing the background, operational track record, and integrity of the sponsor is just as important as the stated return rate.
Private investors often look beyond the preferred rate to evaluate underlying downside protection. A speaker at a Family Office Club event pointed out that investors can ask whether direct investments include pledged collateral, protective voting rights, or separate LLC membership classes to help manage downside risk. Watching for structural warning signs is essential, and you can review our guide on Private Deal Red Flags Every Investor Can Spot before evaluating your next private placement.
Frequently asked questions
What happens to a preferred return if an asset is sold at a loss?
If the sale proceeds do not cover the initial capital invested, investors generally receive whatever remaining capital is available based on their priority position. The sponsor receives no carried interest, but the preferred return target remains unmet and investors absorb the principal loss.
Is a preferred return the same as a debt interest payment?
No. Debt holders have a contractual claim and a lien on specific assets, requiring regular interest payments regardless of company profits. A preferred return is an equity distribution that depends entirely on available cash flow and net profits.
Can a sponsor still earn fees if the preferred return is not reached?
Yes. Sponsors frequently earn ongoing asset management fees, acquisition fees, or operational fees that are paid before investor distributions. However, they are blocked from collecting their performance share or promote until the preferred return hurdle is cleared.
Related reading
- Distribution Waterfalls Explained Step by Step
- What is a typical preferred return in a syndication?
- Retiree Income Investments Checklist
- Income Verification Checklist for Accreditation
- PPM Review Checklist
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club investor event
- The Marketer's Bible by Richard C. Wilson
- Family Office Club mastermind
- SEC Rule 506 (eCFR)
- SEC Rule 205-3, qualified client (eCFR)
