
Understanding the Shift from Growth to Cash Flow
Many investors spend decades focused on capital appreciation in public equities. When retirement approaches, the priority often shifts toward predictable cash generation to cover living expenses.
Public markets offer dividend stocks and municipal or corporate bonds, but yields can fluctuate with broader interest rate cycles. Private market alternatives allow retirees to focus directly on income-producing assets. In private markets, cash flow investing means purchasing an interest in an underlying asset or loan pool and collecting distributions on a monthly, quarterly, or annual schedule.
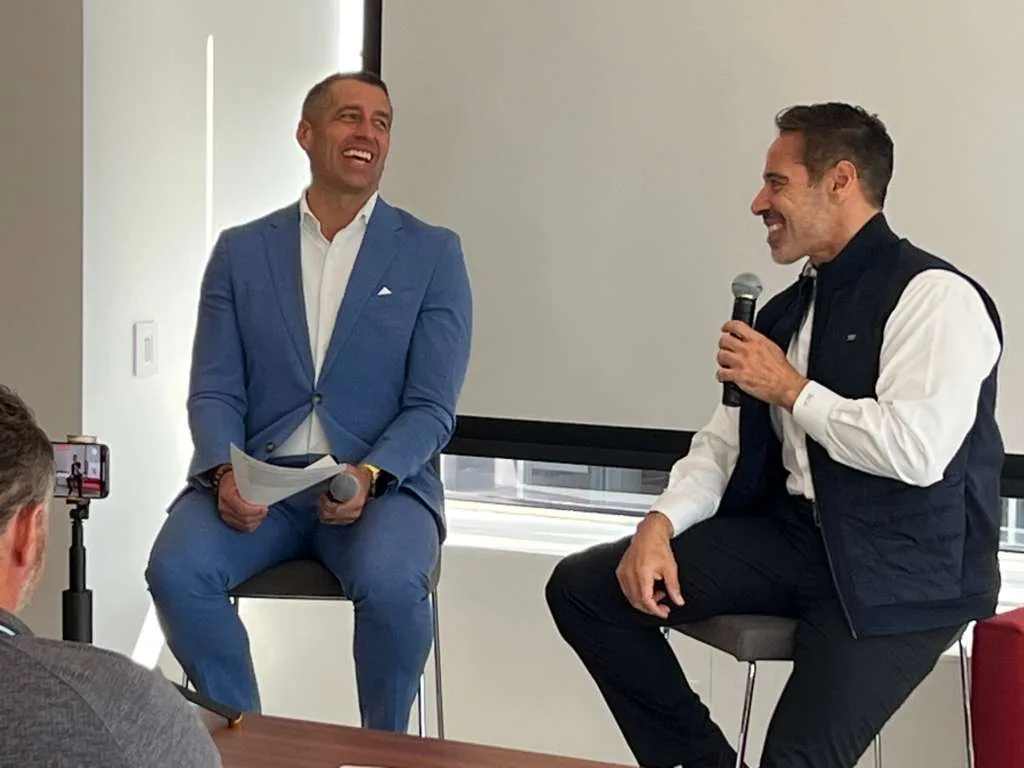
At a Family Office Club workshop, Richard C. Wilson explained that moving from business operations or public equity accumulation to passive cash flow requires a different mindset. Instead of watching daily ticker prices, an income-focused investor examines the stability of the underlying borrower, property tenant, or revenue stream.
Common Private Income Asset Classes
Retirees explore several private structures when building an income portfolio:
- Private Lending and Real Estate Debt: Investors act as the lender for short-term residential or commercial projects. A speaker at a Family Office Club event described how their platform transitioned from direct property development to lending to residential renovators, issuing loans of $150,000 to $7,000,000 over 12 to 18 month terms. Because traditional banks often move slowly, private lenders can capture steady interest distributions secured by the real property.
- Direct Real Estate and Syndications: Commercial properties, multifamily apartments, and hospitality assets generate rental revenue. While some assets face economic cycles, diversified operators often pay regular distributions from operational net cash flow. You can compare pooled models with direct deals in our guide on Private REITs vs Real Estate Syndications.
- Specialty Cash Flow and Royalty Streams: Some private funds focus on cash-flowing operating companies, service businesses, or licensing agreements. You can learn more about these non-traditional structures in our overview of Royalties and Alternative Cash Flow Investments.
Evaluating Illiquidity and Capital Preservation
The main tradeoff for private income yields is illiquidity. Unlike public shares or Treasury bills, private debt and equity commitments cannot be sold instantly with a click.
Federal regulations under Rule 506 classify these assets as restricted securities. Resale is limited, and holding periods apply under SEC rules. For retirees, this structure requires careful cash management:
- Never allocate capital that may be needed for short-term living emergencies.
- Match the duration of the deal with your personal timeline. A 12-month private debt note operates very differently from a 7-year syndication equity hold.
- Look for asset backing. Many retirees favor senior debt or first-lien positions, where the loan is secured by physical real estate or hard company assets.
Before committing capital, review the Retiree Income Investments Checklist to make sure the offering aligns with your personal risk tolerance.
Meeting the Accredited Investor Standards in Retirement
To participate in private offerings, retirees must qualify as accredited investors under SEC Rule 501. The transition from active work to retirement can change how an individual qualifies.
An investor qualifies through either an income test or a net worth test:
- Net Worth Standard: You hold an individual or joint net worth above $1,000,000, excluding the equity value of your primary residence. When calculating this threshold, mortgage debt on the primary home up to its fair market value is excluded as a liability. Assets do not need to be held jointly to count toward the combined total.
- Income Standard: You earned individual income exceeding $200,000 in each of the two most recent years, or joint income exceeding $300,000 with a spouse or spousal equivalent, alongside a reasonable expectation of reaching that level in the current year.
For retirees whose active W-2 earnings have ended, the net worth test is usually the most straightforward path. If you are qualifying with a partner, review our guide on Spousal Equivalent and Joint Qualification to understand how household assets are evaluated.
Situations for Retirees, Pre-Retirees, and First-Time Private Investors
Every investor comes to private income markets from a distinct financial background:
- Pre-Retirees Preparing for an Income Cliff: If you plan to step away from active employment within three to five years, you might begin testing private income deals while your earned income is still high. This allows you to observe distribution reliability before relying on payouts for daily expenses.
- Business Owners After an Exit: Founders who recently sold a company often hold substantial liquidity but lose their monthly operational income. Private credit and asset-backed income funds can replace business cash flow without requiring daily operational oversight.
- First-Time Accredited Investors Transitioning from Public Bonds: If your fixed-income portfolio has yielded less than desired, moving a modest portion of wealth into private lending notes can boost overall portfolio yield. Starting with smaller allocations helps you get comfortable with sponsor reporting and private distribution schedules.
Practical Steps for Reviewing Private Income Deals
When examining private income opportunities, review the sponsor's operational track record and the mechanics of their payout structure:
- Check the Distribution Schedule: Confirm whether payments are made monthly, quarterly, or upon asset sale. For living expenses, monthly distributions are generally preferred.
- Review the Capital Structure: Determine whether your investment is structured as senior debt, mezzanine debt, preferred equity, or common equity. Debt and preferred equity sit higher in the payment waterfall.
- Understand Sponsor Verification: Under Rule 506(c), issuers must take reasonable steps to verify your accredited status using tax returns, asset statements, credit reports, or third-party verification letters. Under Rule 506(b), reasonable belief is required without general advertising.
- Examine Tax Reporting: Most private funds issue annual Schedule K-1 tax forms rather than 1099s. K-1 packages often arrive later in the spring, which may require filing tax extensions.
Frequently asked questions
Can I qualify as an accredited investor if I am fully retired and no longer earn a salary?
Yes. Many retirees qualify using the net worth standard, which requires over $1,000,000 in net worth either individually or jointly with a spouse or spousal equivalent. Your primary residence is excluded from this calculation, but retirement accounts, brokerage accounts, investment properties, and other personal assets count toward the total.
How are distributions from private debt investments typically taxed?
Distributions from private debt and real estate offerings are generally treated as ordinary income or pass-through partnership income depending on the legal structure. Many private funds operate as limited partnerships or LLCs and issue a Schedule K-1 each year detailing interest, returns of capital, or depreciation deductions.
What happens if I need my money back before a private investment matures?
Private investments are restricted securities and lack a public secondary market. Most private income offerings require you to keep your capital committed for the entire agreed term, which may range from one year for bridge loans to five or more years for real estate syndications. You should only invest capital that you do not need for short-term liquidity.
Related reading
- Private Investing for Doctors and Physicians
- 10 Tips for Retirees Seeking Income
- Private Investing for Dentists and Practice Owners
- Real Estate Syndication Due Diligence Checklist
- Farmland and Timber: Real Asset Private Investing
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club investor event
- Family Office Club library reference text
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC Rule 144 (eCFR)
