
Understanding the Shift to Private Markets
Many families start their financial life in traditional public markets before expanding into private equity, venture capital, and commercial real estate. Private market investing offers direct involvement in tangible businesses, yet it requires a completely different mindset. In public markets, assets are liquid and pricing is visible daily. In private investing, capital is committed for years, information is private, and success depends on active evaluation and rigorous deal selection.
In his book on single family offices, Richard C. Wilson writes that many next generation leaders are being prepared as owners rather than day-to-day operators. Instead of running the original operating company, heirs often manage a private holding company structure. This approach lets you learn different industry sectors, review direct opportunities, and direct capital without having to operate every line of business yourself.
Understanding these structures early is essential. Using a structured Next Generation Investor Learning Checklist helps rising leaders build baseline knowledge across fund diligence, governance, and private asset valuation.
Meeting the Regulatory Standards for Private Deals
Before you can participate in most private placements, you must understand the regulatory rules that govern them. Federal securities laws require private offerings under Regulation D to work primarily with accredited investors.
An individual qualifies as an accredited investor by meeting any of these primary standards:
- Individual net worth over $1,000,000, either alone or jointly with a spouse or spousal equivalent, excluding the value of your primary residence.
- Individual income over $200,000 in each of the two most recent years, or joint income over $300,000, with a reasonable expectation of reaching that same level in the current year.
- Holding an active professional certification in good standing, specifically the Series 7, Series 65, or Series 82 license.
Entities also qualify under specific rules. An LLC, trust, or partnership with total assets over $5,000,000, not formed for the specific purpose of acquiring the securities, qualifies as an accredited investor. Furthermore, a family office with more than $5,000,000 in assets under management, directed by a person with financial knowledge and experience, qualifies along with its family clients.
Larger private investment funds operating under Section 3(c)(7) of the Investment Company Act require an even higher standard known as a qualified purchaser. This generally requires an individual or family-owned company to own at least $5,000,000 in investments.
When deals are conducted under Rule 506(c), the issuer must take reasonable steps to verify your accredited status. This verification typically involves providing tax returns, bank statements, or a written letter from a CPA, licensed attorney, or registered broker-dealer dated within the prior three months.
Practical Paths for First-Generation and Next-Generation Wealth
Every family enters private investing from a unique starting point. Here is how different backgrounds shape your approach:
Heirs and Rising Generations
When stepping into established family wealth, your central challenge is often generational dilution. As families expand across second, third, and fourth generations, assets can split quickly among many households. Wealth dilution and market risks cause most multi-generational fortunes to decline significantly after the first two generations. Rising leaders must build formal investment skills rather than relying on informal oversight.
Business Owners Post-Sale
Selling a business creates sudden liquidity. Founders often feel comfortable evaluating operating companies but may be unfamiliar with fund structures, private debt, or passive co-investments. Reviewing How Family Offices Invest in Private Deals can show you how to structure deal flow, evaluate sponsors, and build a balanced direct-investment program.
Windfall and New Money Recipients
Inheriting or creating sudden wealth can feel overwhelming. A common mistake is trying to manage every stock trade, real estate acquisition, and manager allocation alone without adequate staff or processes. Starting small, keeping ample liquidity, and building a trusted team prevents early, costly missteps.
Active Ownership Over Passive Management
A major trap for next generation investors is remaining entirely passive or, conversely, attempting to handle all administrative and investment duties single-handedly.
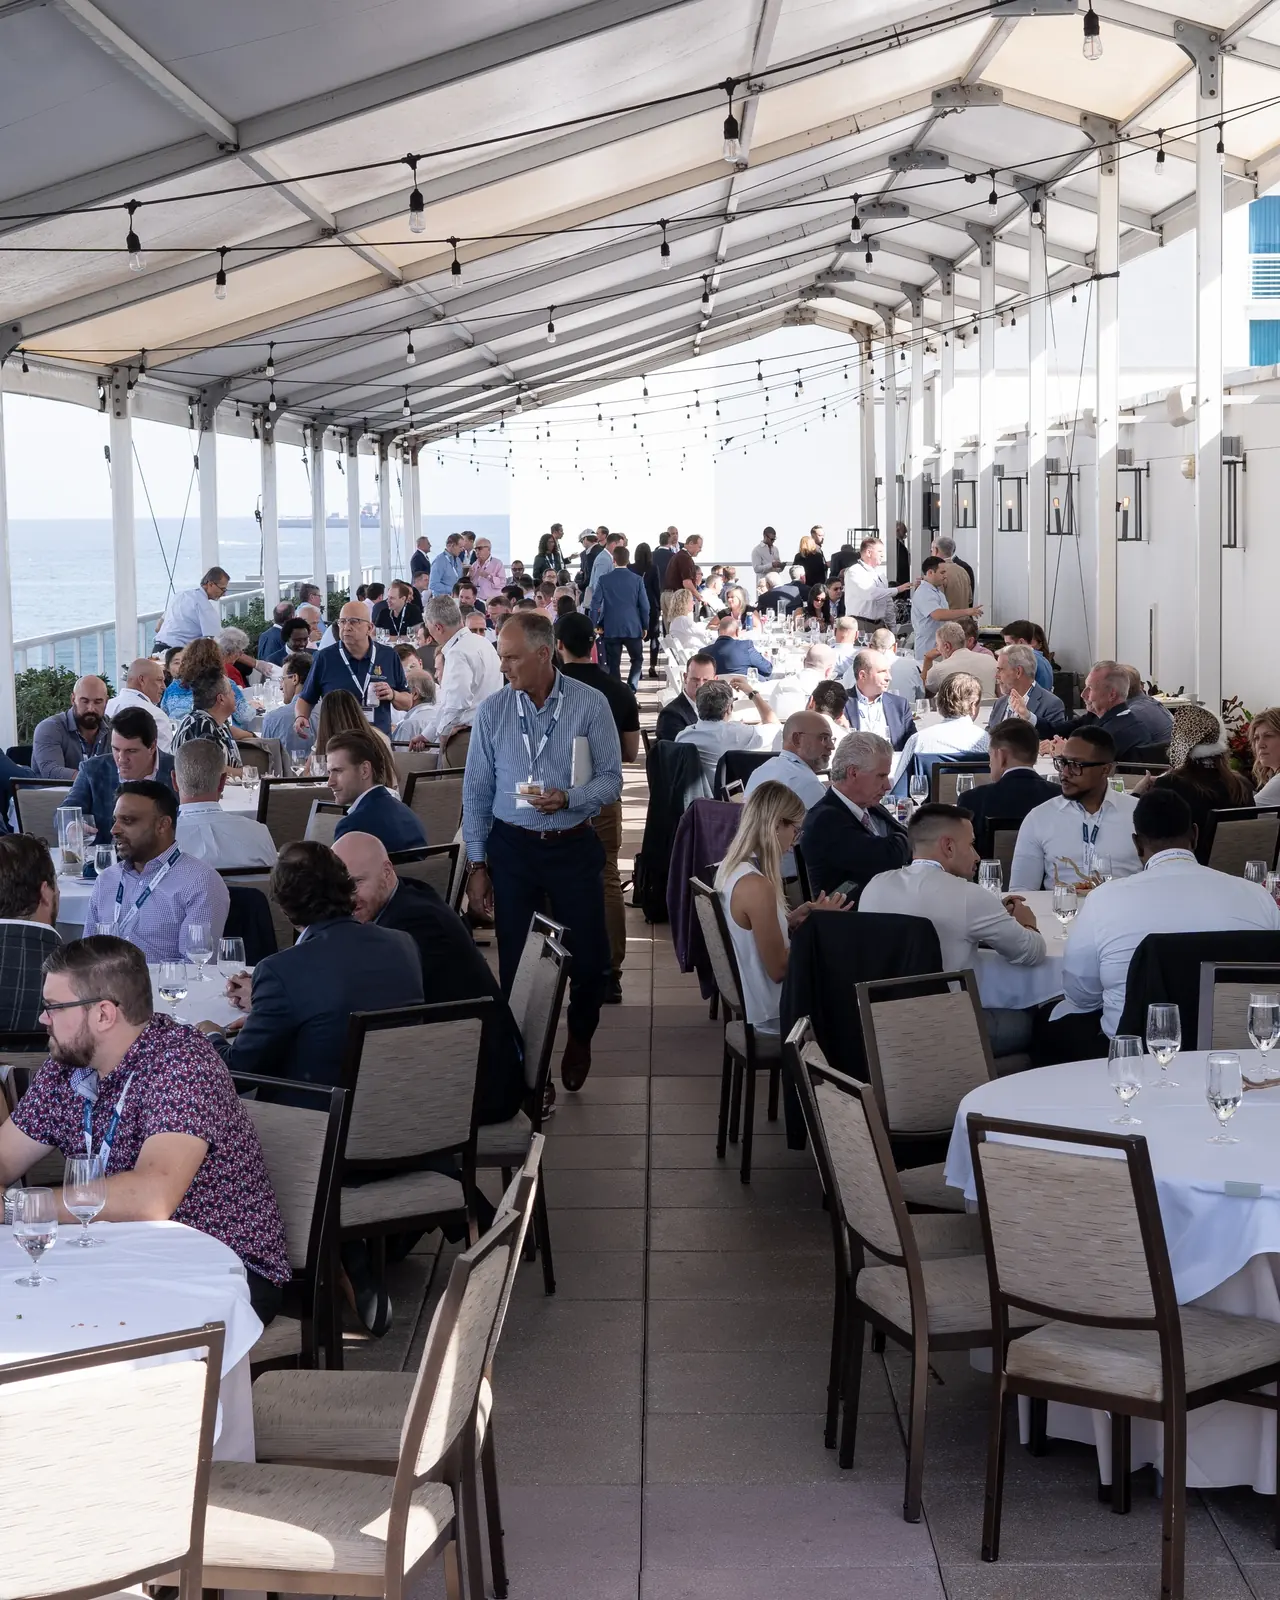
At a Family Office Club event, a speaker emphasized that engaging the next generation early in running real projects builds the practical judgment needed to manage family wealth long term. Waiting decades to involve rising leaders leaves them unprepared when sudden transitions occur.
Active ownership does not mean you must pick every stock or negotiate every real estate lease yourself. It means you understand:
- How investment capital is allocated across asset classes.
- How to read a balance sheet and private placement memorandum.
- How fees, carried interest, and liquidity terms impact overall returns.
- How to ask direct questions of sponsors, fund managers, and operating executives.
By learning to evaluate investment proposals critically, you protect family capital while building your personal reputation in the investment community.
Direct Deals and Co-Investing Strategies
Direct deals allow you to invest directly in private operating companies or commercial properties rather than going through blind-pool funds. While direct investing offers transparency and eliminates fund management fees, it requires substantial diligence.
Many families bridge this gap through collaborative investing. Exploring Co-Investing With Other Families allows you to share due diligence, evaluate sector-specific deals alongside industry veterans, and split transaction expenses. Co-investing provides next generation investors with a masterclass in deal analysis, as you can observe how experienced families structure deal terms, manage risk, and negotiate protections.
Integrating Strategy, Values, and Impact
Rising generations often want their capital to reflect personal values alongside financial targets. Whether focusing on community development, healthcare innovation, or environmental improvements, aligning investments with family values requires clear strategy.
Modern philanthropists and investors succeed most when they bring business discipline to their impact initiatives. Rather than separating charitable giving completely from investing, many families deploy loans, private equity, and direct partnerships to achieve sustainable goals. Balancing passion with clear financial metrics ensures that impact-driven investments remain durable over decades.
Managing Liquidity and Private Commitments
Private investing is inherently illiquid. When you purchase private securities under Rule 506, they are restricted securities. You cannot easily sell them on a public exchange, and holding periods apply under federal rules.
Furthermore, private equity and venture funds often operate on capital call schedules. You commit a set amount of capital, which the fund draws down over several years as deals are sourced. If you fail to maintain enough liquid cash to meet these capital calls, you risk severe contractual penalties. Developing a clear cash management plan ensures your private commitments never compromise your family's short-term liquidity needs.
Frequently asked questions
What is the difference between an accredited investor and a qualified purchaser?
An accredited investor generally needs a net worth over $1,000,000 excluding a primary residence, or annual income over $200,000 individually or $300,000 jointly. A qualified purchaser is a higher regulatory standard requiring an individual or family company to own at least $5,000,000 in investments. Qualified purchaser status is required to access certain private funds formed under Section 3(c)(7).
How can a next generation family member start private investing safely?
Begin by reviewing smaller co-investments alongside seasoned lead investors and studying fund offering documents. Taking time to learn how experienced investors conduct due diligence helps you understand terms and valuation metrics. Committing only a small percentage of your available capital early on protects your portfolio while you build practical experience.
Why do multi-generational wealth transfers frequently fail?
Wealth transfers often struggle due to estate dilution across growing family branches, lack of formal governance, and failure to train the rising generation in active asset management. When heirs receive capital without prior education in risk management and direct investing, assets are quickly eroded by taxes, market downturns, and fragmented decision-making.
Related reading
- 10 Tips for Teaching the Next Generation
- Family Governance and Private Investing
- Founders After an Exit: Becoming an Investor
- After a Business Sale Checklist
- Family Meeting on Private Investments Checklist
- Accredited Investor Test Calculator
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club library reference text
- The Single Family Office, a book by Richard C. Wilson
- Family Office Club investor event
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC Rule 2a51-1, qualified purchaser investments (eCFR)
- SEC Rule 144 (eCFR)
- SEC staff review of the accredited investor definition
