
What Family Governance Means for Direct Investments
At its core, family governance means having clear ground rules for how your family operates and allocates money. Many first-generation wealth creators view governance as unnecessary paperwork. When multiple family members or later generations enter the picture, written policies become essential.
In his book on single family offices, Richard C. Wilson writes that governance acts as the management framework for working together as a family and alongside your professional staff. Without written procedures, families often face conflict caused by favoritism, unmanaged expectations, and inconsistent enforcement of rules.
Clear governance sets standards for how private investments get reviewed, who holds authority to sign contracts, and how distributions occur. It also defines how advisors are vetted, which helps avoid costly mistakes. A lack of independent oversight has led families to suffer heavy losses, including situations where unmonitored advisors allowed major equity positions to be diluted. Documented rules protect both family capital and long-term relationships.
Core Elements of an Investment Governance Framework
A practical governance framework does not need to be overly complex. It should fit the size and operational needs of your family. Most structures include several foundational components:
- Clear Decision-Making Authority: Define who has the power to commit capital. While first-generation offices often rely on a top-down model where the wealth creator decides, growing families usually transition toward formal investment committees.
- Investment Policies and Mandates: Write down the family's risk tolerance, preferred asset classes, target returns, and liquidity requirements.
- Dual Authorization Controls: Protect capital by requiring two signatures on wire transfers, major expenditures, and legal agreements. Wilson notes that simple checks, like dual approvals and routine expenditure reviews, prevent unapproved withdrawals that can go unnoticed for years.
- Advisor Vetting Standards: Establish clear guidelines for selecting, reviewing, and verifying the independence of outside professionals. Learn more about choosing advisors for your family office to ensure their advice remains objective.
- Ethics and Conduct Policies: Create written standards regarding transparency, personal transactions, and how to identify conflicts of interest in private deals.
Adapting Governance for Your Family's Situation
Different families require different governance models depending on their stage of wealth and active involvement in daily management.
Families and the Next Generation
As wealth transitions to second and third generations, informal kitchen-table discussions are no longer enough. Multi-generational families benefit from structured communication, such as family councils or town hall meetings, where members share input. Educating rising generations through junior committee seats helps prepare them to manage direct assets responsibly before they take full control.
Business Owners
Entrepreneurs who sell a company or operate an active enterprise must separate operating company decisions from private portfolio management. Family members who do not work inside the operating business need clear visibility. Providing regular financial reporting, establishing shareholder agreements, and inviting passive members to attend board meetings keeps everyone informed and prevents feelings of exclusion.
Seasoned Investors
Active private investors managing direct deals need systematic due diligence and clear delegation. Even an experienced investor can overlook internal operational risks. Establishing formal review steps and clear approval limits ensures that capital calls and deal allocations are executed efficiently without skipping standard verification.
Building Committees and Communication Channels
As capital grows, families often move from informal chats to structured decision bodies. Many create a dedicated group to evaluate private equity, real estate, and venture opportunities. Reviewing a guide on setting up a family investment committee can help you structure voting rights, meeting rhythms, and member responsibilities.
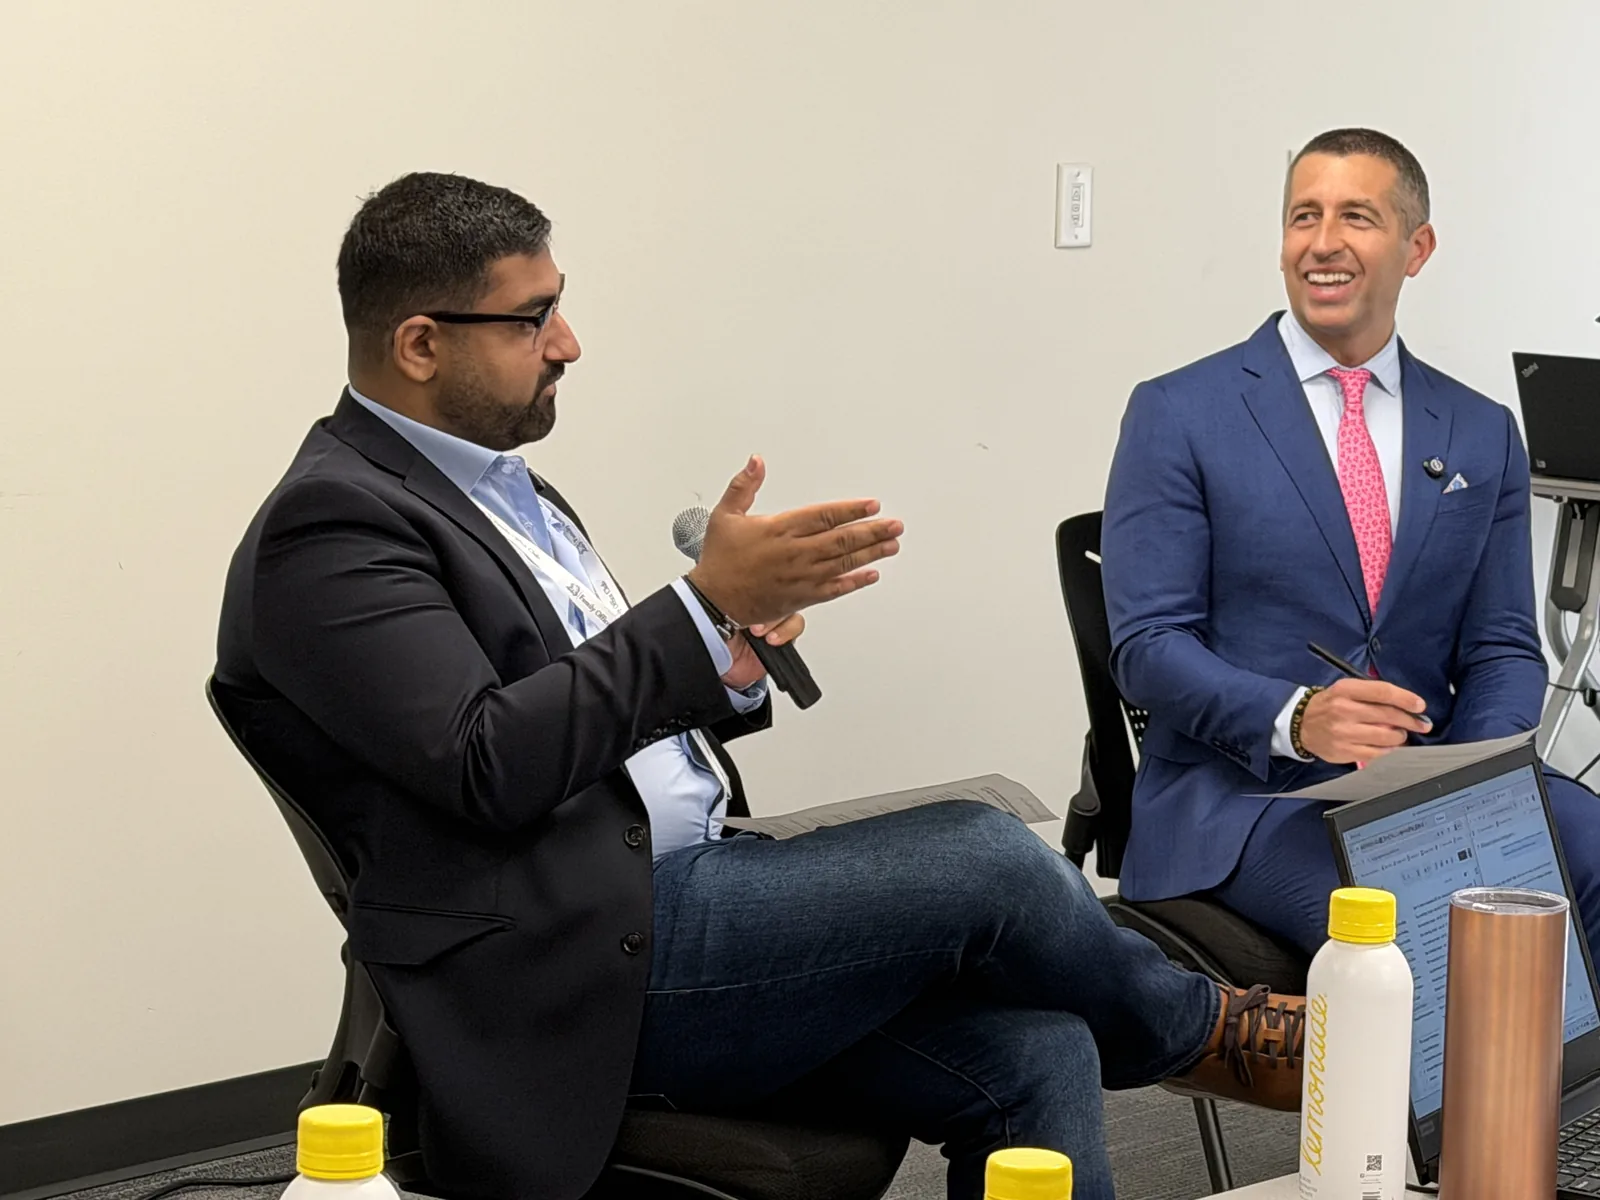
A speaker at a Family Office Club event highlighted four critical pillars for family operational success: consideration, communication, connectivity, and cash. Consideration means exploring and documenting the distinct values and financial needs of each family member. Communication requires regular meetings through family councils or advisory boards. Connectivity ensures that family members share a clear, unified purpose across generations. Cash management requires transparent distribution rules so differing personal financial expectations do not cause family friction.
Meeting Legal and Accredited Investor Standards
Governance structures must align with federal securities regulations. When a family office or private trust makes private investments, the entity itself must meet specific regulatory tests under SEC rules.
Under Rule 501(a)(12) and (13), family offices qualify as accredited investors if they have over $5,000,000 in assets under management, were not formed specifically to buy the securities, and are directed by a person with knowledge and experience in financial and business matters. Their family clients also qualify.
Other family entities can qualify through different regulatory paths:
- Trusts with total assets over $5,000,000 directed by a sophisticated person qualify under Rule 501(a)(7). Revocable trusts can qualify when the grantors meet the individual net worth or income thresholds.
- Legal entities like LLCs or partnerships qualify under Rule 501(a)(3) if their total assets exceed $5,000,000, or under Rule 501(a)(8) if every equity owner is an accredited investor.
- For individuals, qualifying requires a net worth over $1,000,000 alone or with a spouse (excluding the primary residence), or annual income over $200,000 ($300,000 jointly) across the two most recent years with an expectation of the same this year, or a Series 7, 65 or 82 license in good standing.
You can read our guide on entities that qualify as accredited investors to review entity rules in detail, or run your own figures through our accredited investor test calculator.
Keeping Active and Passive Family Members Aligned
A common governance breakdown occurs between family members who work daily inside the investment office and passive stakeholders who do not. Passive members often feel they have little voice and no clear exit options. This disconnect can lead to internal tension, public disputes, or legal action.
In a Family Office Club interview, a governance specialist shared several practical methods to keep passive stakeholders engaged:
- Create a detailed shareholder agreement that outlines shareholder rights, key voting thresholds, and clear distribution rules.
- Name a passive stakeholder as a board representative or board chair to balance perspective between active managers and non-active family members.
- Grant passive stakeholders rights to attend regular board meetings outside of private executive sessions.
- Provide clear, regular financial statements and business plans so everyone understands portfolio performance.
- Keep business debates out of casual social gatherings, or make sure passive members are fully included if portfolio matters are brought up.
When passive stakeholders receive clear updates and fair consideration, the entire family operates with greater unity.
Frequently asked questions
What is the difference between a family council and an investment committee?
A family council focuses on family unity, intergenerational education, shared values, and broad philanthropic goals. An investment committee is a specialized operational group focused on due diligence, asset allocation, portfolio risk, and making direct investment decisions.
How does family governance change from the first generation to later generations?
First-generation governance is usually top-down, with the wealth creator directing all hiring, investing, and spending. Later generations require formal, written rules, structured voting processes, and documented financial controls to manage multiple households, diverse personal goals, and varying levels of business involvement.
Can an informal family group invest in private offerings together?
Private offerings require the investing vehicle or individual to qualify as an accredited investor under federal rules. An informal group cannot simply pool funds without an appropriate legal entity or compliant structure. The entity usually needs over $5,000,000 in assets or must be owned entirely by accredited individuals to participate in private placements under Regulation D.
Related reading
- Co-Investing With Other Families
- How Family Offices Invest in Private Deals
- Next Generation Investor Learning Checklist
- Founders After an Exit: Becoming an Investor
- How Family Offices Find and Source Deals
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- How to Start a Family Office, a book by Richard C. Wilson
- Direct Investments, a book by Richard C. Wilson
- How to Start a Family Office mini-series
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC staff review of the accredited investor definition
