
Where people like you usually start
Seasoned investors often transition from broad blind-pool funds toward direct deals, co-investments, and niche syndications. Once you understand the basics of private placements, your priorities shift toward operational quality, deal flow efficiency, and structural alignment.
Many experienced allocators begin by evaluating how their private assets fit into a cohesive wealth strategy. Using a structured framework like Building a Private Portfolio Over Time helps ensure your commitments match your long-term liquidity profile. At this level, you are likely looking closely at direct sponsor track records rather than relying on brand names.
At a Family Office Club workshop, Richard C. Wilson explained that partnering directly with experienced niche operators often beats trying to build internal operational teams from scratch. Aligning with an operator who brings decades of specialized operational history allows an investor to avoid costly learning curves.
Seasoned investors also look for collaborative deal structures. Many choose Co-Investing With Other Families to share the burden of deep diligence, negotiate better economics, and secure larger allocations in competitive opportunities.
Questions to settle first
Before deploying fresh capital into new private assets, experienced allocators review several structural points:
- Entity and Tax Structure. Are you investing as an individual, through a family trust, or via an operating business? Many investors ask Can I invest through my own LLC? to maintain liability protection and simplify estate planning.
- Fund Regulatory Classification. Are you entering a standard 3(c)(1) fund or a 3(c)(7) fund? Understanding 3(c)(1) vs 3(c)(7) Funds: What It Means for You is essential, as 3(c)(7) funds require you to meet the higher qualified purchaser standard of owning at least $5,000,000 in investments under Section 2(a)(51) of the Investment Company Act.
- Offering Exemption Dynamics. Understanding Rule 506(b) vs 506(c): What Investors Should Know keeps verification painless. Rule 506(b) offerings allow reasonable belief based on existing relationships, while Rule 506(c) offerings permit general solicitation and require reasonable verification steps, such as letters from licensed CPAs, attorneys, or registered investment advisers.
- Adviser Compensation Standards. If an investment adviser charges performance-based carried interest, you must usually meet the qualified client threshold under Rule 205-3, which requires at least $1,400,000 under management with the adviser or a joint net worth exceeding $2,700,000.
Common mistakes to avoid
Even active, knowledgeable investors occasionally run into avoidable pitfalls in private transactions.
- Evaluating only the positive track record. At a Family Office Club workshop, Richard C. Wilson highlighted that understanding what happened when a deal went sideways is often more informative than looking at successful exits. Ask sponsors how they managed difficult market conditions, debt maturities, or operational setbacks.
- Skipping bad actor verification. Federal securities rules disqualify offerings under Rule 506 if covered persons have relevant criminal convictions or regulatory orders. Reviewing The Bad Actor Rule and How It Protects Investors reminds us why background checks remain a vital final step.
- Overlooking capital call pacing. In private equity funds, unfunded commitments create legal obligations. Seasoned investors map out cash buffers in advance to prevent default terms from triggering.
- Rushing wire instructions. Wire fraud targeting private real estate and fund closings is common. Using a structured verification step such as the Before You Wire Funds Checklist prevents routing errors and compromised account losses.
Your reading path
Explore these resources to refine your investment process and portfolio reviews:
- Building a Private Portfolio Over Time - A guide to balancing liquidity, diversification, and asset classes across private holdings.
- 3(c)(1) vs 3(c)(7) Funds: What It Means for You - Clarifies the statutory differences and investor qualification standards for private funds.
- Rule 506(b) vs 506(c): What Investors Should Know - Details how issuer advertising rules impact the documentation you provide to verify accredited status.
- The Bad Actor Rule and How It Protects Investors - Explains the disqualification provisions that keep fraudulent operators out of Regulation D offerings.
- Co-Investing With Other Families - Explores deal syndication, shared diligence, and governance when investing alongside peers.
- Annual Review of Private Holdings Checklist - A structured template to audit sponsor reporting, tax documents, and valuation updates every year.
- Before You Wire Funds Checklist - Practical safety steps to verify banking instructions and avoid wiring fraud before closing.
- Co-Investment Evaluation Checklist - A due diligence tool for evaluating direct sidecar investments and single-asset syndications.
- 15 Tips for Asking Sponsors Better Questions - Sharp questions on fee structures, watermarks, sponsor co-investment, and conflict management.
- 12 Tips for Attending Investor Events - Actionable ideas for vetting peers, meeting operators, and filtering deal flow at conferences.
Frequently asked questions
How do experienced investors verify an accredited status without revealing sensitive financial statements?
In Rule 506(c) offerings, you can avoid sharing full tax returns or bank statements by providing a written verification letter from a qualified third party. This includes an SEC-registered investment adviser, a registered broker-dealer, a licensed attorney, or a certified public accountant who has reviewed your qualifications within the prior three months. Additionally, under an SEC staff position, making a high minimum investment of at least $200,000 for natural persons or $1,000,000 for entities, along with written representations, can serve as a reasonable verification step.
What are the main liquidity constraints when holding restricted private securities?
Securities purchased through private placements under Rule 506 are restricted securities under federal law. You cannot freely trade them on public exchanges. Reselling these securities usually requires qualifying for a specific exemption, such as Rule 144, which includes mandatory holding periods and volume restrictions. Most private fund agreements and operating agreements also grant the general partner or manager discretion over whether to approve secondary transfers.
What is the difference between an accredited investor and a qualified purchaser?
An accredited investor is an individual with over $1,000,000 in net worth excluding their primary residence, or annual income over $200,000 individually ($300,000 jointly) over the past two years. A qualified purchaser is held to a higher standard under Section 2(a)(51) of the Investment Company Act, generally requiring an individual to own at least $5,000,000 in qualifying investments. Private funds structured under Section 3(c)(7) are limited to qualified purchasers, allowing them to raise capital from up to 1,999 investors without registering as an investment company.
Related reading
- Find your starting point
- Accredited Investor Test Calculator
- Private Investor Due Diligence Mini-Series
- Family Office Club events and membership
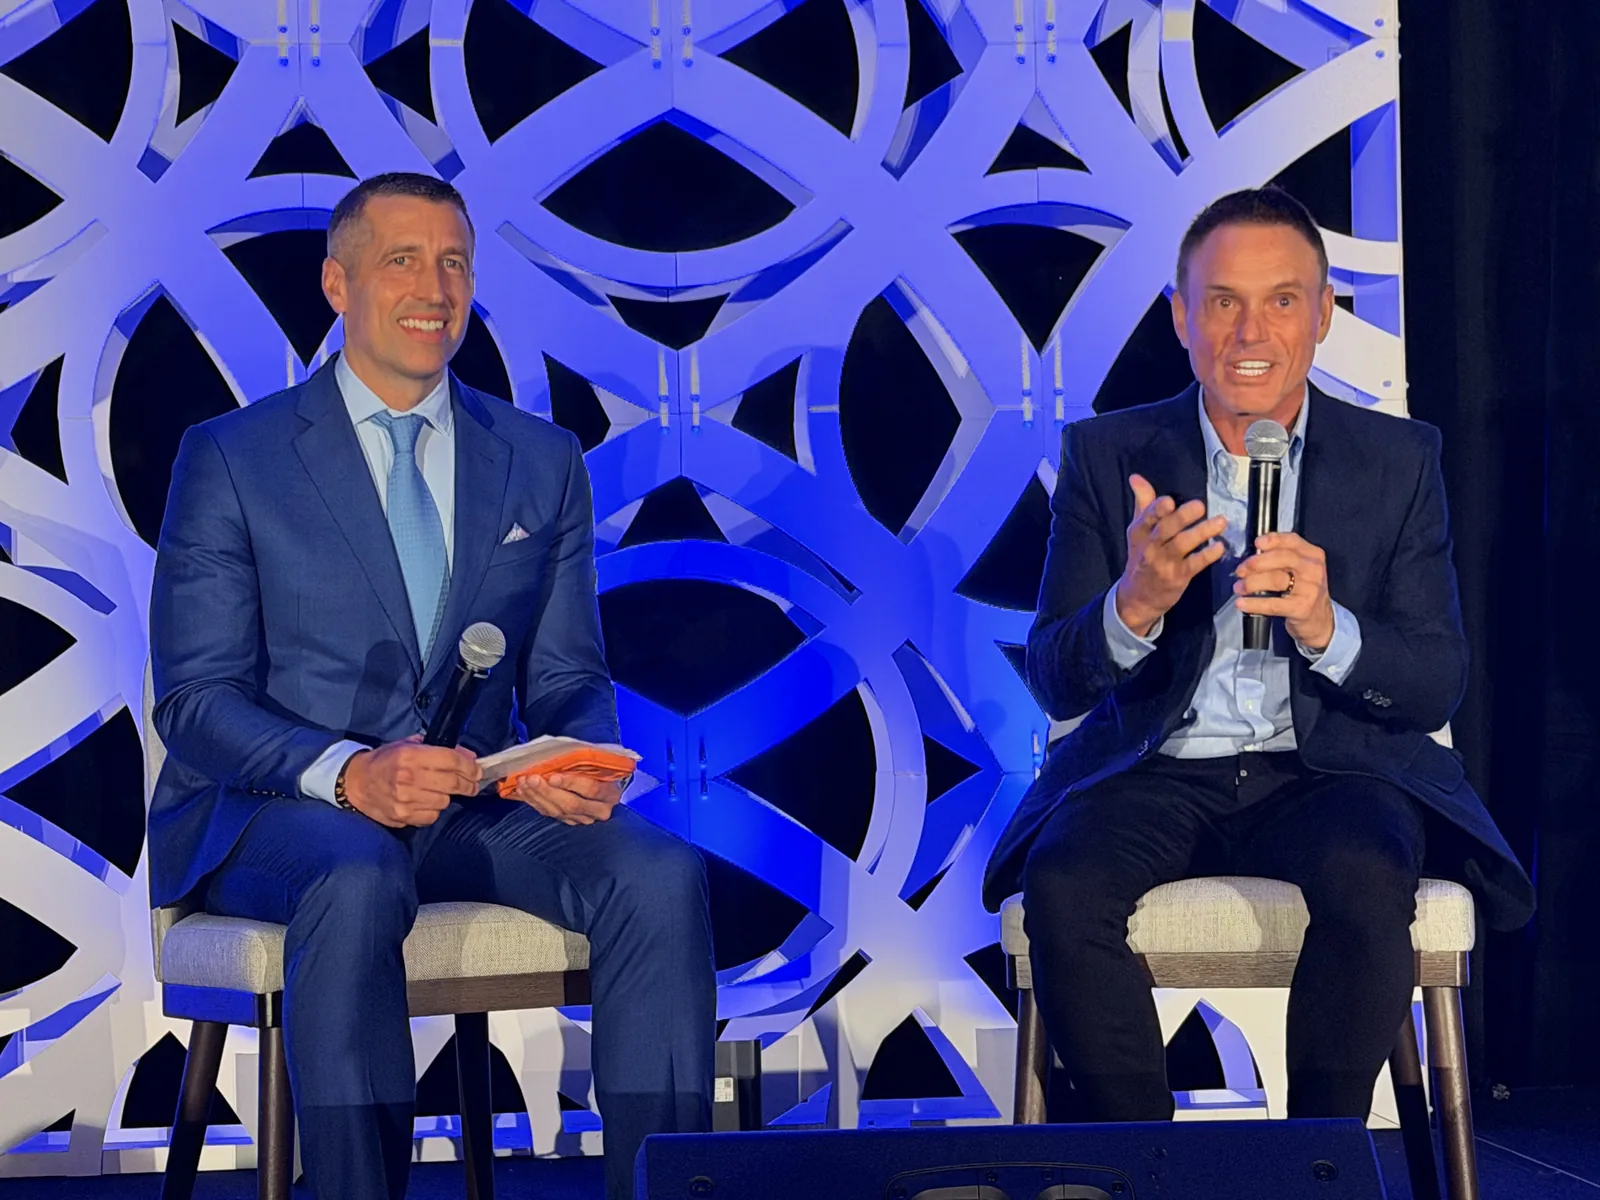
This site is built from over 19 years of Family Office Club workshops, bootcamps, masterminds and investor events. The club has 17 million registered LinkedIn group members, 19 million social media followers in total, 345 events held and $1B in transactions completed between our members.
Sources
- Family Office Club library reference text
- Family Office Club billionaire fireside interview
- Family Office Club workshop
- SEC Rule 501(a), definition of accredited investor (eCFR)
- SEC Rule 506 (eCFR)
- SEC: Accredited investors
- SEC Rule 205-3, qualified client (eCFR)
- SEC Rule 2a51-1, qualified purchaser investments (eCFR)
- SEC Rule 144 (eCFR)
